Accounting for Partnership: Basic Concepts — Chapter Summary
Madhya Pradesh Board · Class 12 · Accountancy
Summary of Accounting for Partnership: Basic Concepts for Madhya Pradesh Board Class 12 Accountancy. Partnership accounting deals with the financial.
Interactive on Super Tutor
Studying Accounting for Partnership: Basic Concepts? Get the full interactive chapter.
Quizzes, flashcards, AI doubt-solver and a step-by-step study plan — built for chapter summary and more.
Free trial, no card needed.
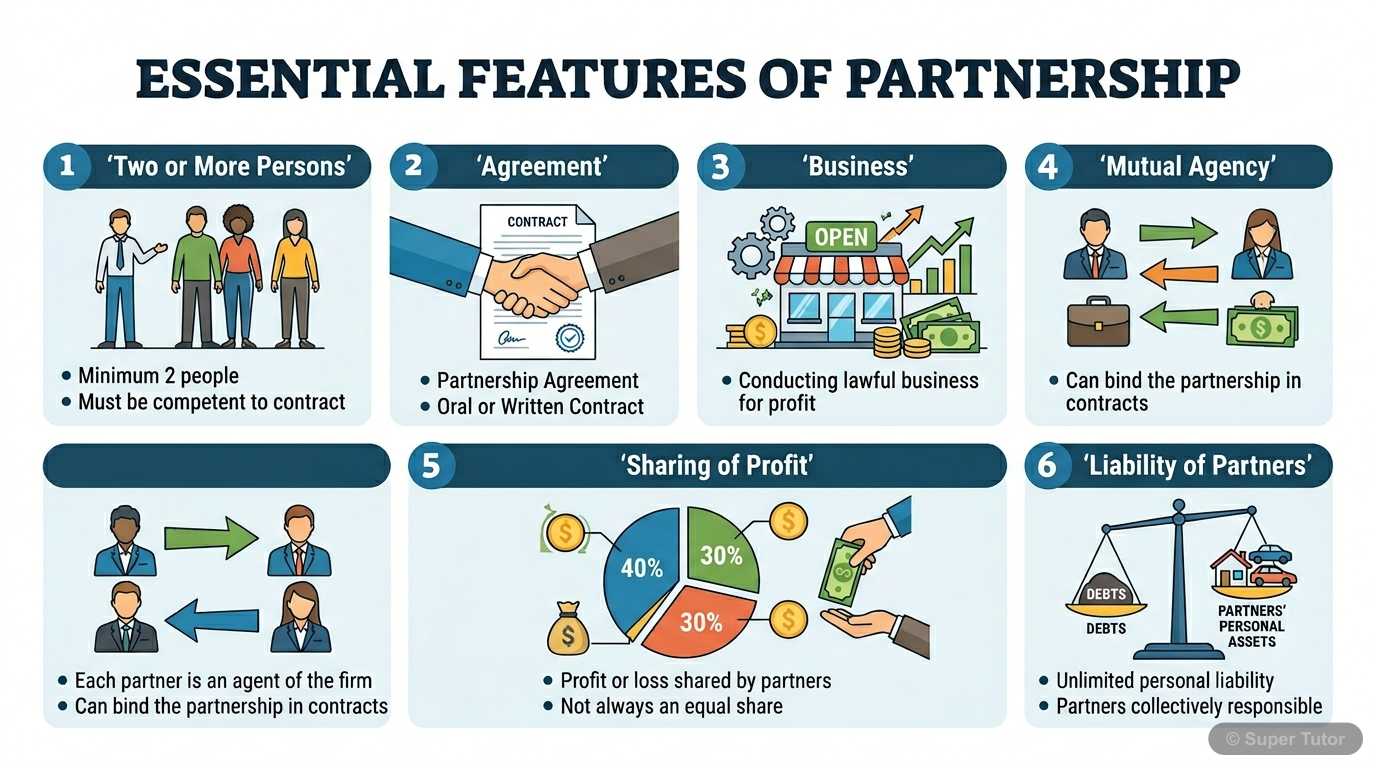
One of 10 illustrations for Accounting for Partnership: Basic Concepts in Super Tutor — alongside flashcards, concept maps and practice questions.
Overview
Partnership accounting deals with the financial records of a firm formed by two or more persons who agree to share profits and losses and act for one another. A partnership firm has no separate legal entity apart from the partners, so the accounting treatment focuses on partners’ capital, profit sha
Key Concepts
Partnership is the relation between persons
Partnership is the relation between persons who have agreed to share the profits of a business carried on by all or any of them acting for all. Its ma
The partnership deed is the written
The partnership deed is the written document containing the terms of partnership, though an oral agreement is also valid. It may cover capital contrib
If no agreement exists on
If no agreement exists on a matter, profits are shared equally, no interest is allowed on capital, no interest is charged on drawings, a partner’s loa
Under the fixed capital method
Under the fixed capital method, two accounts are maintained for each partner: capital account and current account. Under the fluctuating capital metho
This account is an extension
This account is an extension of the Profit and Loss Account. It shows how profit or loss is appropriated among partners after adjustments such as inte
Learning Objectives
- Define partnership and identify its essential features
- Understand the role of the Partnership Deed and default legal provisions
- Distinguish between fixed capital method and fluctuating capital method
- Prepare Profit and Loss Appropriation Account
- Calculate interest on capital and interest on drawings under different situations
Frequently Asked Questions
What are the important topics in Accounting for Partnership: Basic Concepts for Madhya Pradesh Board Class 12 Accountancy?
How should I revise Accounting for Partnership: Basic Concepts for the Madhya Pradesh Board Class 12 board exam?
Sources & Official References
Content is aligned to the official syllabus. Refer to the board website for the latest curriculum.
More resources for Accounting for Partnership: Basic Concepts
Practice Quiz
Test yourself with a quick quiz
Important Questions
Exam-style questions with answers
Revision Notes
Key points for last-minute revision
Concept Maps
See how topics connect
Study Plan
Step-by-step plan for this chapter
Flashcards
Quick-fire cards for active recall
Syllabus
What topics to cover
NCERT Solutions
Every textbook question solved step by step
For serious students
Get the full Accounting for Partnership: Basic Concepts chapter — start free.
Quizzes, flashcards, an AI doubt solver and a study plan for Madhya Pradesh Board Class 12 Accountancy. Free to start, no card needed.