Accounting for Partnership: Basic Concepts — Revision Notes
Madhya Pradesh Board · Class 12 · Accountancy
Accounting for Partnership: Basic Concepts revision notes for Madhya Pradesh Board Class 12 Accountancy: 4 topics in quick points.
Interactive on Super Tutor
Studying Accounting for Partnership: Basic Concepts? Get the full interactive chapter.
Quizzes, flashcards, AI doubt-solver and a step-by-step study plan — built for revision notes and more.
Free trial, no card needed.
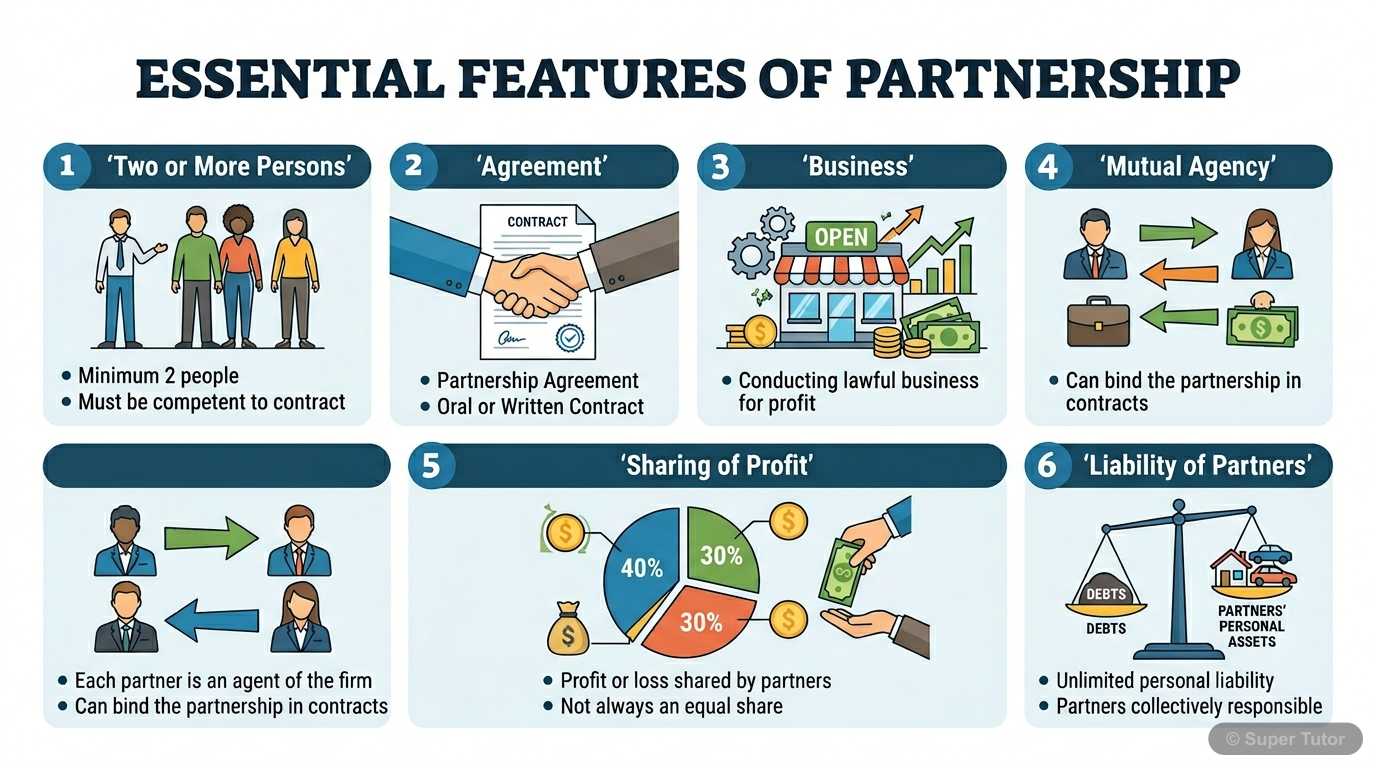
One of 10 illustrations for Accounting for Partnership: Basic Concepts in Super Tutor — alongside flashcards, concept maps and practice questions.
Key Topics to Revise
1. Nature of Partnership
- Partnership is the relation between persons who have agreed to share the profits of a business carried on by all or any of them acting for all.
- A partnership firm has no separate legal entity apart from the partners constituting it.
- The minimum number of partners is two.
2. Partnership Deed and Default Rules
- The partnership deed contains the terms and conditions of partnership.
- The deed may include capital contribution, profit-sharing ratio, interest on capital, interest on loan, salaries, commission, and rules for admission, retirement, death, and dissolution.
- The deed can be altered only with the consent of all partners.
3. Capital Accounts of Partners
- All transactions relating to partners are recorded through capital accounts.
- There are two methods: fixed capital method and fluctuating capital method.
- Under fixed capital method, two accounts are maintained for each partner: capital account and current account.
4. Distribution of Profit and Loss
- Profits and losses are distributed among partners in the agreed ratio.
- If the deed is silent, profits and losses are shared equally.
- Profit and Loss Appropriation Account is prepared to show distribution of profit among partners.
Get complete notes with diagrams and examples
Full NotesKey Concepts
Frequently Asked Questions
What are the important topics in Accounting for Partnership: Basic Concepts for Madhya Pradesh Board Class 12 Accountancy?
How should I revise Accounting for Partnership: Basic Concepts for the Madhya Pradesh Board Class 12 board exam?
Sources & Official References
Content is aligned to the official syllabus. Refer to the board website for the latest curriculum.
More resources for Accounting for Partnership: Basic Concepts
Practice Quiz
Test yourself with a quick quiz
Important Questions
Exam-style questions with answers
Chapter Summary
Understand the chapter at a glance
Concept Maps
See how topics connect
Study Plan
Step-by-step plan for this chapter
Flashcards
Quick-fire cards for active recall
Syllabus
What topics to cover
NCERT Solutions
Every textbook question solved step by step
For serious students
Get the full Accounting for Partnership: Basic Concepts chapter — start free.
Quizzes, flashcards, an AI doubt solver and a study plan for Madhya Pradesh Board Class 12 Accountancy. Free to start, no card needed.