Partnership Accounts : Fundamentals of Partnership — Chapter Summary
ICSE · Class 12 · Accountancy
Summary of Partnership Accounts : Fundamentals of Partnership for ICSE Class 12 Accountancy. Part of the ICSE Class 12 Accountancy syllabus.
Interactive on Super Tutor
Studying Partnership Accounts : Fundamentals of Partnership? Get the full interactive chapter.
Quizzes, flashcards, AI doubt-solver and a step-by-step study plan — built for chapter summary and more.
Free trial, no card needed.
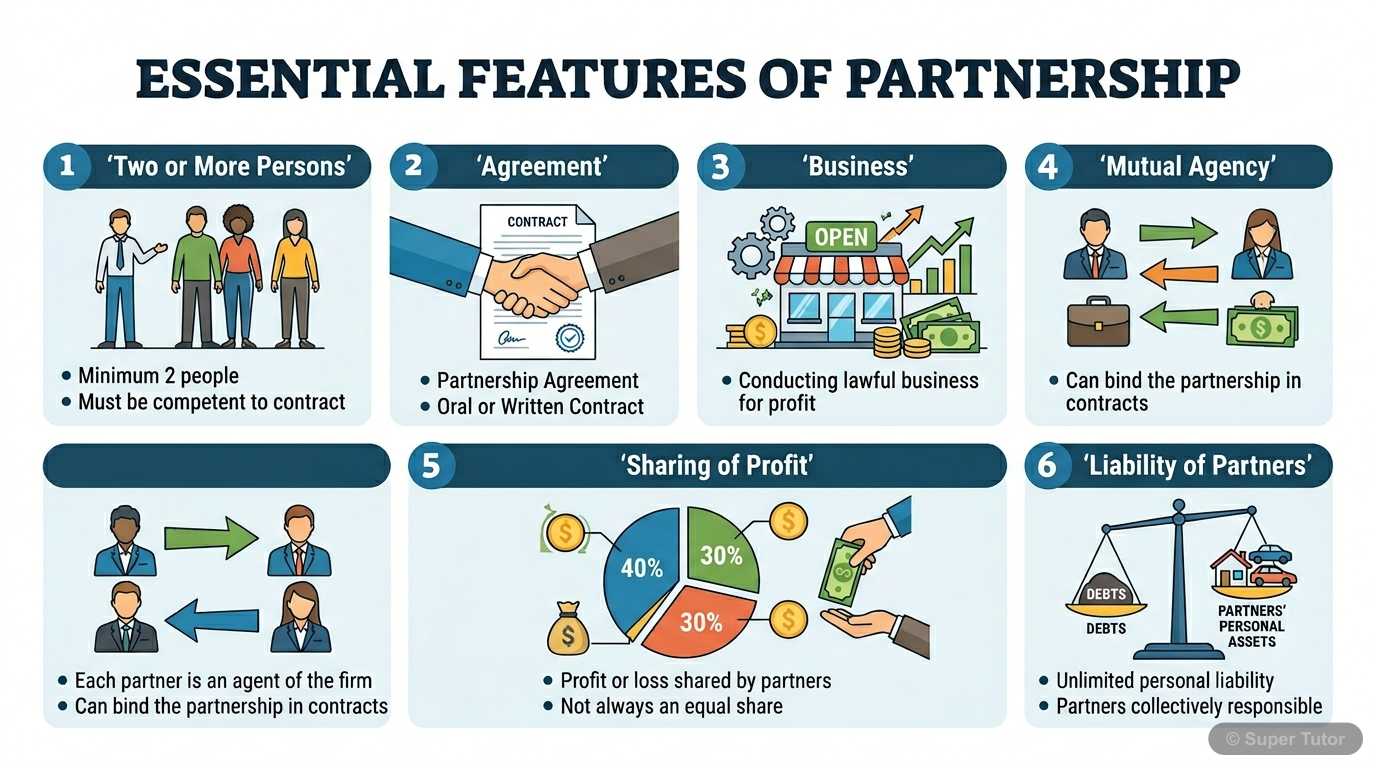
One of 10 illustrations for Partnership Accounts : Fundamentals of Partnership in Super Tutor — alongside flashcards, concept maps and practice questions.
Overview
Partnership is a business relationship in which two or more persons agree to share profits of a business carried on by all or any of them acting for all. In partnership accounts, the main focus is on the meaning of partnership, essential features, partnership deed, rules applied when no deed exists,
Key Concepts
Partnership is the relation between persons
Partnership is the relation between persons who have agreed to share the profits of a business carried on by all or any of them acting for all. A part
A partnership requires at least two
A partnership requires at least two persons, an agreement, business with profit motive, sharing of profits, agency relationship, and business carried
A written
A written, signed, and duly stamped agreement among partners is called the Partnership Deed, Articles of Partnership, or Constitution of Partnership F
If there is no deed
If there is no deed or the deed is silent, profits and losses are shared equally, no interest is allowed on capital, no interest is charged on drawing
This account is an extension
This account is an extension of the Profit and Loss Account. It shows how net profit is distributed among partners after adjustments such as interest
Learning Objectives
- Understand the meaning and definition of partnership
- Identify the essential features of a partnership firm
- Explain the importance and contents of a partnership deed
- Apply the legal rules used when no partnership deed exists
- Distinguish between charge against profit and appropriation out of profit
Frequently Asked Questions
What are the important topics in Partnership Accounts : Fundamentals of Partnership for ICSE Class 12 Accountancy?
How should I revise Partnership Accounts : Fundamentals of Partnership for the ICSE Class 12 board exam?
Sources & Official References
Content is aligned to the official syllabus. Refer to the board website for the latest curriculum.
More resources for Partnership Accounts : Fundamentals of Partnership
For serious students
Get the full Partnership Accounts : Fundamentals of Partnership chapter — start free.
Quizzes, flashcards, an AI doubt solver and a study plan for ICSE Class 12 Accountancy. Free to start, no card needed.