Dissolution of Partnership Firm — Revision Notes
Madhya Pradesh Board · Class 12 · Accountancy
Dissolution of Partnership Firm revision notes for Madhya Pradesh Board Class 12 Accountancy: 4 topics in quick points.
Interactive on Super Tutor
Studying Dissolution of Partnership Firm? Get the full interactive chapter.
Quizzes, flashcards, AI doubt-solver and a step-by-step study plan — built for revision notes and more.
Free trial, no card needed.
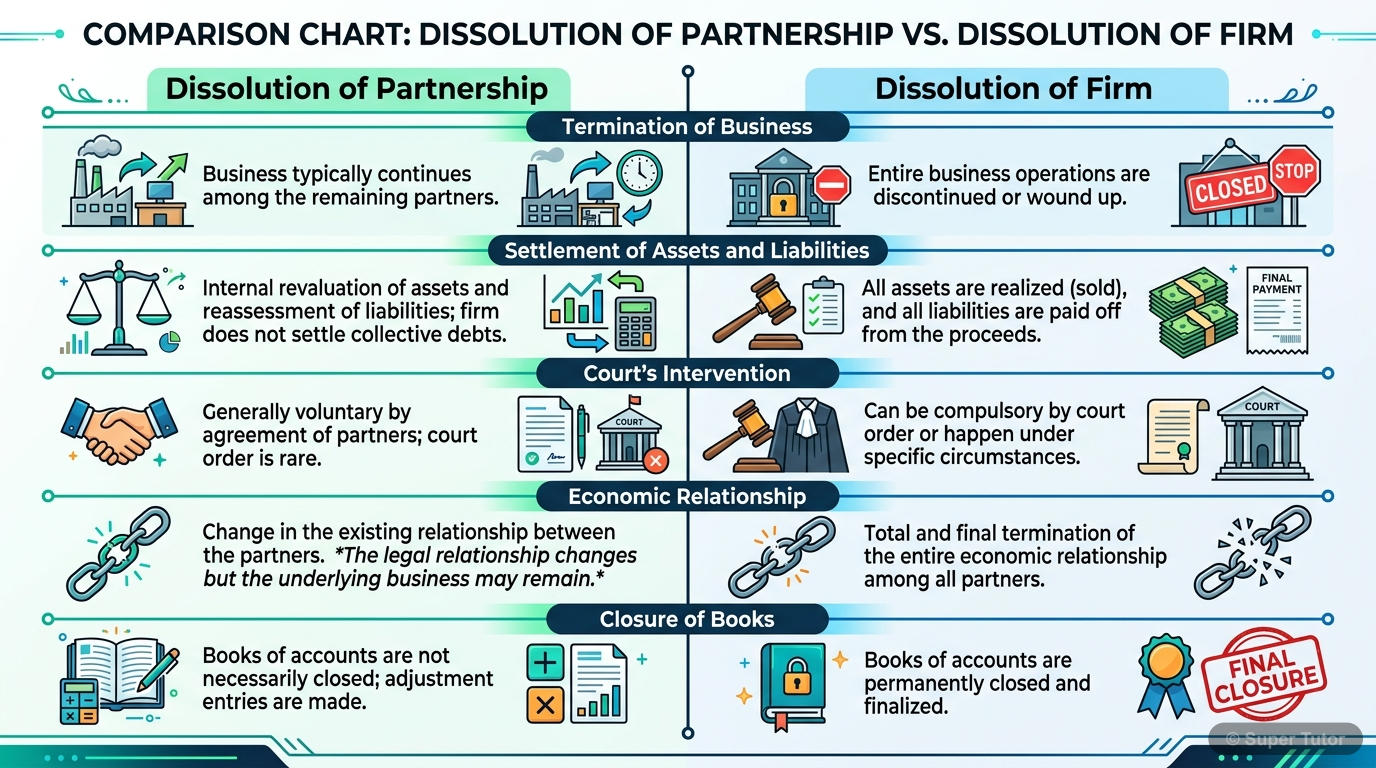
Learn better with visuals Super Tutor pairs illustrations like this with notes and quizzes for Dissolution of Partnership Firm.
Key Topics to Revise
1. Meaning and Difference Between Dissolution of Partnership and Dissolution of Firm
- Dissolution of partnership changes the existing relationship between partners, but the firm may continue its business as before.
- Dissolution of partnership can happen due to change in profit sharing ratio, admission of a new partner, retirement, death, insolvency of a partner, completion of venture, or expiry of period.
- Dissolution of partnership firm means dissolution of partnership between all the partners of a firm.
2. Modes of Dissolution of Firm
- A firm can be dissolved by agreement with consent of all partners or according to the contract between partners.
- Dissolution may happen without court intervention or by court order.
- Compulsory dissolution occurs when all partners or all but one partner become insolvent, when the business becomes illegal, or when an event makes the business unlawful, such as a partner becoming an
3. Settlement of Accounts Under Section 48 and Section 49
- Losses, including deficiencies of capital, are paid first out of profits, next out of capital of partners, and lastly by the partners individually in their profit sharing ratio.
- The assets of the firm are applied first to debts of the firm to third parties, then to partners' advances or loans, then to partners' capital, and the residue is divided in profit sharing ratio.
- Secured loans have precedence over unsecured loans when paying outside liabilities.
4. Insolvency of a Partner and Garner vs Murray Principle
- If a partner cannot contribute towards the deficiency of his capital account, he is insolvent.
- The sum not recoverable from an insolvent partner is treated as capital loss for the firm.
- In the absence of agreement to the contrary, the capital loss is borne by the remaining solvent partners in the ratio of their capitals as on the date of dissolution.
Get complete notes with diagrams and examples
Full NotesKey Concepts
Frequently Asked Questions
What are the important topics in Dissolution of Partnership Firm for Madhya Pradesh Board Class 12 Accountancy?
How should I revise Dissolution of Partnership Firm for the Madhya Pradesh Board Class 12 board exam?
Sources & Official References
Content is aligned to the official syllabus. Refer to the board website for the latest curriculum.
More resources for Dissolution of Partnership Firm
Practice Quiz
Test yourself with a quick quiz
Important Questions
Exam-style questions with answers
Formula Sheet
The chapter's formulas in one place
Chapter Summary
Understand the chapter at a glance
Concept Maps
See how topics connect
Study Plan
Step-by-step plan for this chapter
Flashcards
Quick-fire cards for active recall
Syllabus
What topics to cover
NCERT Solutions
Every textbook question solved step by step
For serious students
Get the full Dissolution of Partnership Firm chapter — start free.
Quizzes, flashcards, an AI doubt solver and a study plan for Madhya Pradesh Board Class 12 Accountancy. Free to start, no card needed.