Cash Flow Statement — Revision Notes
Madhya Pradesh Board · Class 12 · Accountancy
Cash Flow Statement revision notes for Madhya Pradesh Board Class 12 Accountancy: 4 topics in quick points. Includes Meaning, Need, and Legal Basis, Cash.
Interactive on Super Tutor
Studying Cash Flow Statement? Get the full interactive chapter.
Quizzes, flashcards, AI doubt-solver and a step-by-step study plan — built for revision notes and more.
Free trial, no card needed.
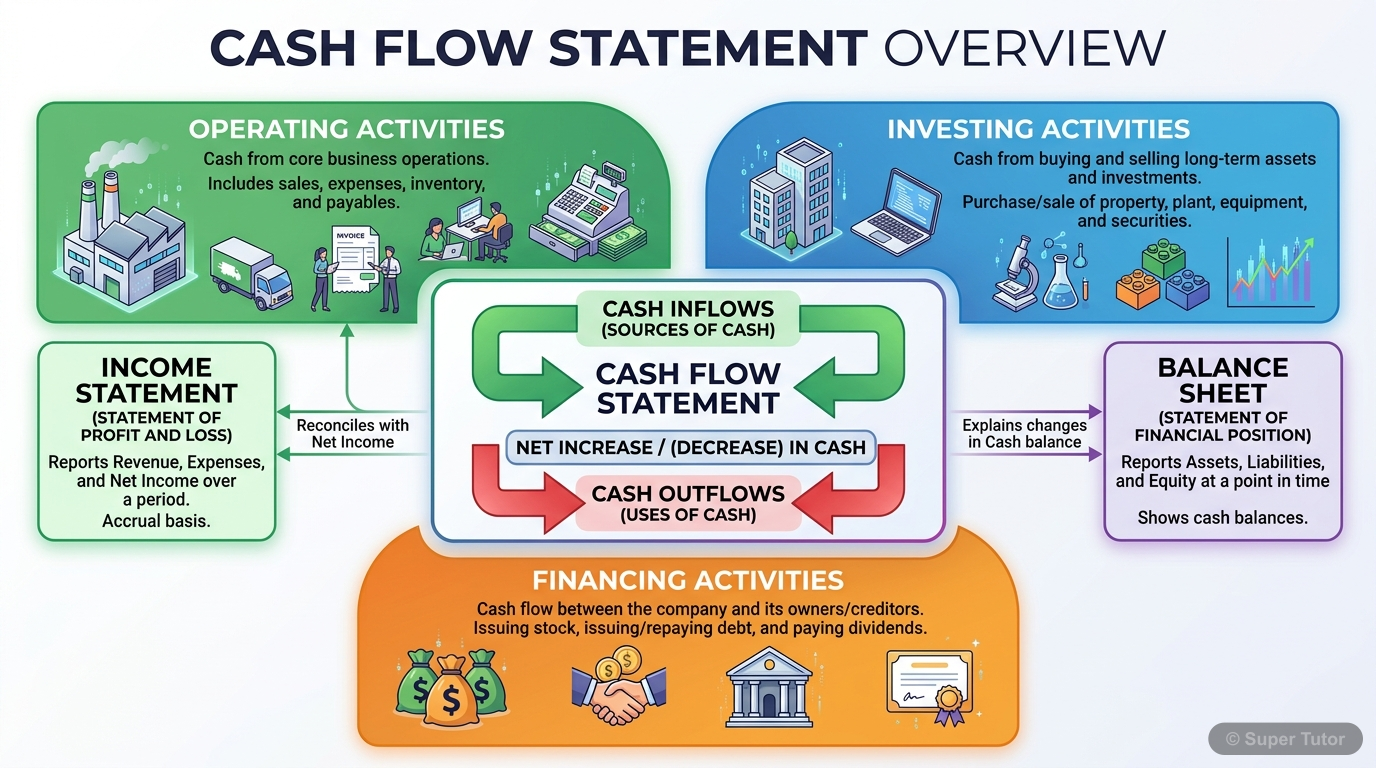
One of 6 illustrations for Cash Flow Statement in Super Tutor — alongside flashcards, concept maps and practice questions.
Key Topics to Revise
1. Meaning, Need, and Legal Basis
- Cash Flow Statement shows cash inflows and cash outflows for a specific period.
- It is different from Position Statement and Income Statement.
- It is one of the financial statements of a company.
2. Cash, Cash Equivalents, and Cash Flows
- Cash comprises cash in hand and demand deposits with banks.
- Cash equivalents are short-term highly liquid investments readily convertible into known amounts of cash with insignificant risk of value change.
- An investment normally qualifies as cash equivalent only if its maturity is three months or less from the date of acquisition.
3. Classification of Cash Flows
- Cash flows are classified into operating, investing, and financing activities.
- Operating activities are the principal revenue generating activities of the enterprise and are not investing or financing activities.
- Investing activities are acquisition and disposal of long-term assets and other investments not included in cash equivalents.
4. Special Items and Their Treatment
- In a financial enterprise, interest paid, interest received, and dividend received are operating activities, while dividend paid is financing.
- In a non-financial enterprise, payment of interest and dividends are financing activities, while receipt of interest and dividends are investing activities.
- Tax on operating profit is operating.
Get complete notes with diagrams and examples
Full NotesKey Concepts
Frequently Asked Questions
What are the important topics in Cash Flow Statement for Madhya Pradesh Board Class 12 Accountancy?
How should I revise Cash Flow Statement for the Madhya Pradesh Board Class 12 board exam?
Sources & Official References
Content is aligned to the official syllabus. Refer to the board website for the latest curriculum.
More resources for Cash Flow Statement
Practice Quiz
Test yourself with a quick quiz
Important Questions
Exam-style questions with answers
Formula Sheet
The chapter's formulas in one place
Chapter Summary
Understand the chapter at a glance
Concept Maps
See how topics connect
Study Plan
Step-by-step plan for this chapter
Flashcards
Quick-fire cards for active recall
Syllabus
What topics to cover
NCERT Solutions
Every textbook question solved step by step
For serious students
Get the full Cash Flow Statement chapter — start free.
Quizzes, flashcards, an AI doubt solver and a study plan for Madhya Pradesh Board Class 12 Accountancy. Free to start, no card needed.