Cash Flow Statement — NCERT Solutions
Madhya Pradesh Board · Class 12 · Accountancy
NCERT Solutions for Cash Flow Statement, Madhya Pradesh Board Class 12 Accountancy: 29 textbook questions solved step by step.
Interactive on Super Tutor
Studying Cash Flow Statement? Get the full interactive chapter.
Quizzes, flashcards, AI doubt-solver and a step-by-step study plan — built for NCERT solutions and more.
Free trial, no card needed.
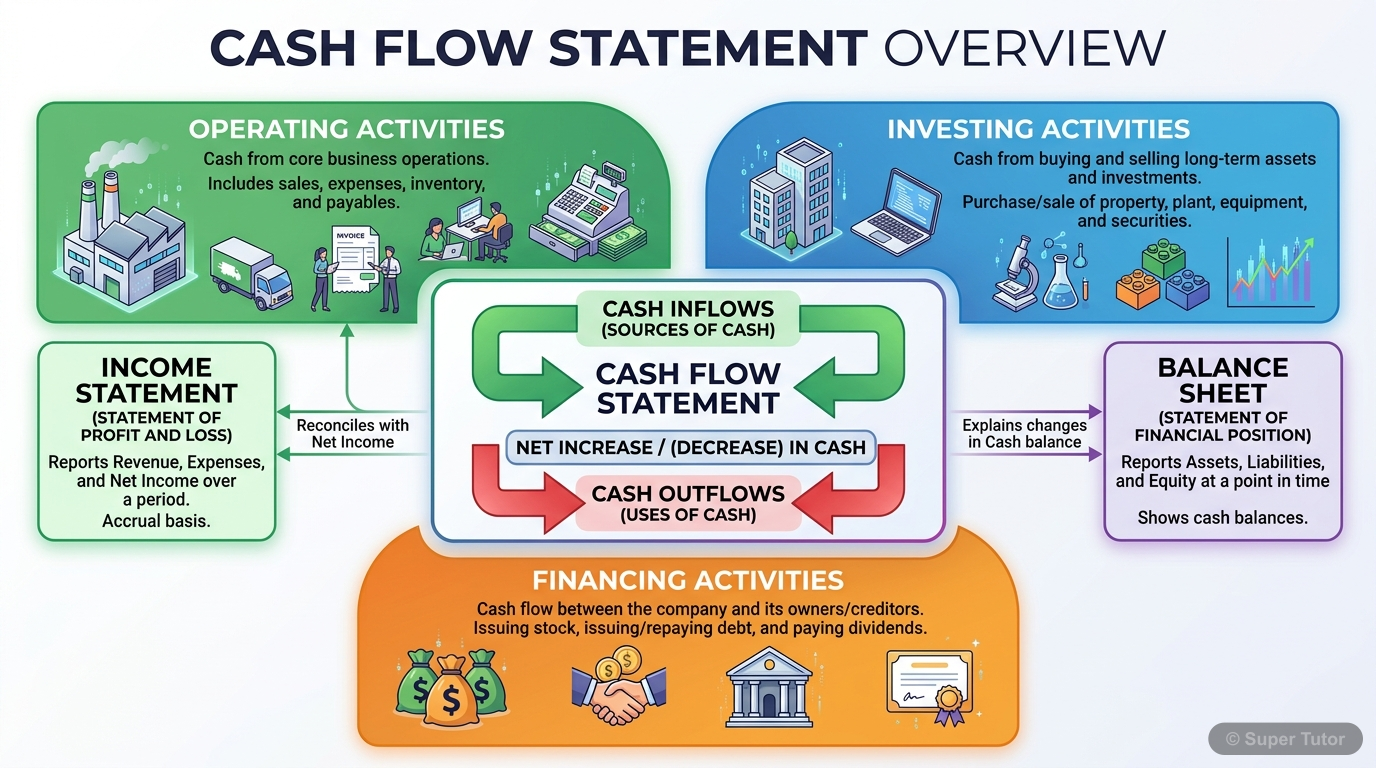
One of 6 illustrations for Cash Flow Statement in Super Tutor — alongside flashcards, concept maps and practice questions.
The first 15 solutions are open to read. The other 14 are free with a Super Tutor account.
Test your Understanding - I
1Classify the following activities into operating activities, investing activities, financing activities, cash equivalents:
1. Purchase of machinery.
2. Proceeds from issue of equity share capital.
3. Cash revenue from operations.
4. Proceeds from long-term borrowings.
5. Proceeds from sale of old machinery.
6. Cash receipt from trade receivables.
7. Trading commission received.
8. Purchase of non-current investment.
9. Redemption of preference shares.
10. Cash purchases.
11. Proceeds from sale of non-current investment.
12. Purchase of goodwill.
13. Cash paid to supplier.
14. Interim dividend paid on equity shares.
15. Employee benefits expenses paid.
16. Proceeds from sale of patents.
17. Interest received on debentures held as investments.
18. Interest paid on long-term borrowings.
19. Office and administrative expenses paid.
20. Manufacturing overheads paid.
21. Dividend received on shares held as investment.
22. Rent received on property held as investment.
23. Selling and distribution expenses paid.
24. Income tax paid.
25. Dividend paid on preference shares.
26. Under-writing commission paid.
27. Rent paid.
28. Brokerage paid on purchase of non-current investment.
29. Bank overdraft.
30. Cash credit.
31. Short-term deposit.
32. Marketable securities.
32. Refund of income-tax received.Show solution
Classification of Activities:
Operating Activities (main revenue-generating activities of the enterprise):
- 3. Cash revenue from operations
- 6. Cash receipt from trade receivables
- 7. Trading commission received
- 10. Cash purchases
- 13. Cash paid to supplier
- 15. Employee benefits expenses paid
- 18. Interest paid on long-term borrowings (for non-financial enterprises, as per AS-3)
- 19. Office and administrative expenses paid
- 20. Manufacturing overheads paid
- 23. Selling and distribution expenses paid
- 24. Income tax paid
- 25. Dividend paid on preference shares (can also be financing; commonly treated as operating or financing)
- 27. Rent paid
- 32. Refund of income-tax received
Investing Activities (acquisition and disposal of long-term assets and investments):
- 1. Purchase of machinery
- 5. Proceeds from sale of old machinery
- 8. Purchase of non-current investment
- 11. Proceeds from sale of non-current investment
- 12. Purchase of goodwill
- 16. Proceeds from sale of patents
- 17. Interest received on debentures held as investments
- 21. Dividend received on shares held as investment
- 22. Rent received on property held as investment
- 28. Brokerage paid on purchase of non-current investment
Financing Activities (activities that result in changes in size and composition of owners' capital and borrowings):
- 2. Proceeds from issue of equity share capital
- 4. Proceeds from long-term borrowings
- 9. Redemption of preference shares
- 14. Interim dividend paid on equity shares
- 26. Under-writing commission paid
Cash Equivalents (short-term, highly liquid investments readily convertible to cash):
- 29. Bank overdraft (cash equivalent — negative cash)
- 30. Cash credit (cash equivalent — negative cash)
- 31. Short-term deposit
- 32. Marketable securities
Note: Under AS-3 (Revised), interest paid and dividends paid may be classified as operating or financing activities; interest received and dividends received may be classified as operating or investing activities. The above classification follows the most common treatment for non-financial enterprises.
Test your Understanding - II
1Choose one of the two alternatives given below and fill in the blanks:
(a) If the net profits earned during the year is Rs. 50,000 and the amount of debtors in the beginning and the end of the year is Rs. 10,000 and Rs. 20,000 respectively, then the cash from operating activities will be equal to Rs. ___________ (Rs. 40,000/Rs. 60,000)
(b) If the net profits made during the year are Rs. 50,000 and the bills receivables have decreased by Rs. 10,000 during the year then the cash flow from operating activities will be equal to Rs. ___________ (40,000/Rs. 60,000)
(c) Expenses paid in advance at the end of the year are ___________ the profit made during the year (added to/deducted from).
(d) An increase in accrued income during the particular year is ___________ the net profit (added to/deducted from).
(e) Goodwill amortised is ___________ the profit made during the year for calculating the cash flow from operating activities (added to/deducted from).
(f) For calculating cash flow from operating activities, provision for doubtful debts is ___________ the profit made during the year (added to/deducted from).Show solution
(a) Net Profit = Rs. 50,000; Debtors increased by Rs. 20,000 − Rs. 10,000 = Rs. 10,000 (increase in debtors means less cash collected, so deduct).
Answer: Rs. 40,000
(b) Net Profit = Rs. 50,000; Bills Receivables decreased by Rs. 10,000 (decrease in bills receivables means more cash collected, so add).
Answer: Rs. 60,000
(c) Expenses paid in advance (prepaid expenses) at the end of the year represent cash paid but not yet charged to profit. They are deducted from the profit made during the year.
Answer: deducted from
(d) An increase in accrued income means income has been recognised in profit but cash has not been received. Therefore, it is deducted from the net profit.
Answer: deducted from
(e) Goodwill amortised is a non-cash charge that has been debited to the Statement of Profit and Loss, thereby reducing profit. Since no cash is paid, it is added to the profit made during the year.
Answer: added to
(f) Provision for doubtful debts is a non-cash charge that reduces profit. Since no cash outflow occurs, it is added to the profit made during the year.
Answer: added to
2While computing cash from operating activities, indicate whether the following items will be added or subtracted from the net profit — if not to be considered, write NC:
(a) Increase in the value of creditors
(b) Increase in the value of patents
(c) Decrease in prepaid expenses
(d) Decrease in income received in advance
(e) Decrease in value of inventory
(f) Increase in share capital
(g) Increase in the value of trade receivables
(h) Increase in the amount of outstanding expenses
(i) Conversion of debentures into shares
(j) Decrease in the value of trade payables
(k) Increase in the value of trade receivables
(l) Decrease in the amount of accrued incomeShow solution
Concept: Under the indirect method, net profit is adjusted for:
- Non-cash items and non-operating items
- Changes in working capital (current assets and current liabilities)
Increase in current liability → Add (more cash retained)
Decrease in current liability → Subtract (cash paid out)
Increase in current asset → Subtract (cash used)
Decrease in current asset → Add (cash released)
| Item | Treatment |
|---|---|
| (a) Increase in the value of creditors (Trade Payables) | Added — increase in current liability means less cash paid |
| (b) Increase in the value of patents | NC — purchase of patents is an investing activity, not an operating working capital item |
| (c) Decrease in prepaid expenses | Added — decrease in current asset releases cash |
| (d) Decrease in income received in advance | Subtracted — decrease in current liability means cash was not received for this portion |
| (e) Decrease in value of inventory | Added — decrease in current asset releases cash |
| (f) Increase in share capital | NC — it is a financing activity |
| (g) Increase in the value of trade receivables | Subtracted — increase in current asset uses cash |
| (h) Increase in the amount of outstanding expenses | Added — increase in current liability means expense recognised but cash not yet paid |
| (i) Conversion of debentures into shares | NC — it is a non-cash financing activity |
| (j) Decrease in the value of trade payables | Subtracted — decrease in current liability means cash was paid out |
| (k) Increase in the value of trade receivables | Subtracted — same as (g); increase in current asset uses cash |
| (l) Decrease in the amount of accrued income | Added — decrease in current asset (accrued income) means cash was received |
Do it Yourself
1From the following particulars, calculate cash flows from investing activities:
| | Purchased Rs. | Sold Rs. |
|---|---|---|
| Plant | 4,40,000 | 50,000 |
| Investments | 1,80,000 | 1,00,000 |
| Goodwill | 2,00,000 | — |
| Patents | — | 1,00,000 |
Interest received on debentures held as investment Rs. 60,000
Dividend received on shares held as investment Rs. 10,000
A plot of land had been purchased for investment purposes and was let out for commercial use and rent received Rs. 30,000.Show solution
Given:
- Plant purchased: Rs. 4,40,000; Plant sold: Rs. 50,000
- Investments purchased: Rs. 1,80,000; Investments sold: Rs. 1,00,000
- Goodwill purchased: Rs. 2,00,000
- Patents sold: Rs. 1,00,000
- Interest received: Rs. 60,000
- Dividend received: Rs. 10,000
- Rent received on investment land: Rs. 30,000
Cash Flows from Investing Activities:
| Particulars | Rs. | Rs. |
|---|---|---|
| Cash outflow for purchase of Plant | (4,40,000) | |
| Cash inflow from sale of Plant | 50,000 | |
| Cash outflow for purchase of Investments | (1,80,000) | |
| Cash inflow from sale of Investments | 1,00,000 | |
| Cash outflow for purchase of Goodwill | (2,00,000) | |
| Cash inflow from sale of Patents | 1,00,000 | |
| Interest received on debentures (investing) | 60,000 | |
| Dividend received on shares (investing) | 10,000 | |
| Rent received on investment land | 30,000 | |
| Net Cash used in Investing Activities | (4,70,000) |
2From the following information, calculate cash flows from investing and financing activities:
| Particulars | 2016 | 2017 |
|---|---|---|
| Machine at cost | 5,00,000 | 9,00,000 |
| Accumulated Depreciation | 3,00,000 | 4,50,000 |
| Equity Share Capital | 28,00,000 | 35,00,000 |
| Bank Loan | 12,50,000 | 7,50,000 |
In year 2017, machine costing Rs. 2,00,000 was sold at a profit of Rs. 1,50,000. Depreciation charged on machine during the year 2017 amounted to Rs. 2,50,000.Show solution
Step 1: Find Book Value and Sale Proceeds of Machine Sold
Machine sold: Cost = Rs. 2,00,000
Accumulated depreciation on sold machine:
Using Machine Account (at cost):
Using Accumulated Depreciation Account:
Book Value of machine sold = Rs. 2,00,000 − Rs. 1,00,000 = Rs. 1,00,000
Sale proceeds = Book Value + Profit = Rs. 1,00,000 + Rs. 1,50,000 = Rs. 2,50,000
Cash Flows from Investing Activities:
| Particulars | Rs. |
|---|---|
| Purchase of Machine (outflow) | (6,00,000) |
| Proceeds from sale of Machine (inflow) | 2,50,000 |
| Net Cash used in Investing Activities | (3,50,000) |
Step 2: Financing Activities
Equity Share Capital increased: Rs. 35,00,000 − Rs. 28,00,000 = Rs. 7,00,000 (inflow)
Bank Loan repaid: Rs. 12,50,000 − Rs. 7,50,000 = Rs. 5,00,000 (outflow)
Cash Flows from Financing Activities:
| Particulars | Rs. |
|---|---|
| Proceeds from issue of Equity Share Capital | 7,00,000 |
| Repayment of Bank Loan | (5,00,000) |
| Net Cash from Financing Activities | 2,00,000 |
Short Answer Questions
1What is a Cash Flow Statement?Show solution
Cash Flow Statement is a financial statement that shows the inflows (receipts) and outflows (payments) of cash and cash equivalents during a specific accounting period.
- It is prepared as per Accounting Standard-3 (AS-3) Revised, which is mandatory for all companies under the Companies Act, 2013.
- It classifies cash flows into three categories:
- Operating Activities — principal revenue-generating activities
- Investing Activities — acquisition and disposal of long-term assets
- Financing Activities — activities that change the size and composition of capital and borrowings
- It helps users assess the ability of the enterprise to generate cash and cash equivalents and the needs of the enterprise to utilise those cash flows.
2How are the various activities classified (as per AS-3 revised) while preparing cash flow statement?Show solution
As per AS-3 (Revised), cash flows are classified into three categories:
1. Operating Activities:
- These are the principal revenue-producing activities of the enterprise.
- Examples: Cash received from customers, cash paid to suppliers, cash paid to employees, income tax paid, etc.
2. Investing Activities:
- These involve the acquisition and disposal of long-term assets and other investments not included in cash equivalents.
- Examples: Purchase/sale of fixed assets, purchase/sale of investments, interest received, dividend received.
3. Financing Activities:
- These are activities that result in changes in the size and composition of the owners' capital and borrowings of the enterprise.
- Examples: Proceeds from issue of shares/debentures, repayment of loans, payment of dividends, interest paid.
The net increase or decrease in cash = Cash from Operating + Investing + Financing Activities.
3State the objectives of cash flow statement.Show solution
Objectives of Cash Flow Statement:
- Liquidity Assessment: To assess the ability of the enterprise to generate cash and cash equivalents.
- Cash Planning: To help management plan and coordinate financial operations by forecasting future cash needs.
- Comparison: To enable comparison of operating performance of different enterprises by eliminating the effects of different accounting treatments.
- Solvency Check: To evaluate the solvency of the enterprise — whether it can meet its short-term and long-term obligations.
- Basis for Decision Making: To provide information useful for making economic decisions.
- Reconciliation: To reconcile the difference between net profit and net cash flow from operating activities.
- Evaluation of Investing and Financing Decisions: To show how the enterprise has used its cash resources in investing and financing activities.
4What are the objectives of preparing cash flow statement?Show solution
The objectives of preparing a Cash Flow Statement are:
- To assess liquidity and solvency of the business — whether the enterprise can generate sufficient cash to meet its obligations.
- To provide information about cash inflows and outflows from operating, investing, and financing activities.
- To help in short-term financial planning — management can plan cash requirements in advance.
- To evaluate the ability of the enterprise to generate cash from operations.
- To facilitate comparison of cash flow performance across different enterprises and different periods.
- To explain the difference between net profit and net cash flow from operations.
- To assess the impact of investing and financing decisions on the financial position of the enterprise.
(Note: Questions 3 and 4 are similar; both relate to objectives of Cash Flow Statement.)
5State the meaning of the terms: (i) Cash Equivalents, (ii) Cash flows.Show solution
(i) Cash Equivalents:
Cash equivalents are short-term, highly liquid investments that are:
- Readily convertible into known amounts of cash, and
- Subject to an insignificant risk of changes in value.
Examples: Treasury bills, commercial paper, money market funds, short-term government bonds (maturity of 3 months or less from the date of acquisition).
Bank overdrafts and cash credits are also treated as cash equivalents (negative cash) as they form an integral part of cash management.
(ii) Cash Flows:
Cash flows refer to inflows and outflows of cash and cash equivalents during an accounting period.
- Cash Inflows: Receipts of cash or cash equivalents (e.g., cash received from customers, proceeds from sale of assets).
- Cash Outflows: Payments of cash or cash equivalents (e.g., cash paid to suppliers, purchase of fixed assets).
Cash flows exclude movements between items that constitute cash or cash equivalents (e.g., transfer from bank account to cash in hand).
6Prepare a format of cash flow from operating activities.Show solution
Format of Cash Flow from Operating Activities (Indirect Method):
| Particulars | Rs. | Rs. |
|---|---|---|
| Net Profit before Tax and Extraordinary Items | xxx | |
| Adjustments for non-cash and non-operating items: | ||
| Add: Depreciation | xxx | |
| Add: Amortisation of Goodwill/Patents | xxx | |
| Add: Loss on sale of Fixed Assets | xxx | |
| Add: Provision for Doubtful Debts | xxx | |
| Less: Profit on sale of Fixed Assets | (xxx) | |
| Less: Dividend/Interest Income (investing) | (xxx) | |
| xxx | ||
| Operating Profit before Working Capital Changes | xxx | |
| Adjustments for changes in Working Capital: | ||
| Add: Decrease in Current Assets | xxx | |
| Add: Increase in Current Liabilities | xxx | |
| Less: Increase in Current Assets | (xxx) | |
| Less: Decrease in Current Liabilities | (xxx) | |
| Cash Generated from Operations | xxx | |
| Less: Income Tax Paid | (xxx) | |
| Net Cash from Operating Activities | xxx |
7State clearly what would constitute the operating activities for each of the following enterprises:
(i) Hotel
(ii) Film production house
(iii) Financial enterprise
(iv) Media enterprise
(v) Steel manufacturing unit
(vi) Software development business unit.Show solution
Operating activities are the principal revenue-generating activities of an enterprise. They differ based on the nature of the business:
(i) Hotel:
- Cash received from guests for room rent, food, beverages, and other services
- Cash paid to suppliers for food, beverages, and housekeeping materials
- Cash paid to employees (salaries, wages)
- Cash paid for utilities, maintenance, and administrative expenses
(ii) Film Production House:
- Cash received from distributors and exhibitors for films produced
- Cash received from sale of music rights, satellite rights, OTT rights
- Cash paid to artists, directors, technicians, and crew
- Cash paid for production expenses (sets, costumes, equipment hire)
(iii) Financial Enterprise (e.g., Bank, NBFC):
- Cash received as interest on loans and advances given
- Cash received as dividends on investments
- Cash paid as interest on deposits and borrowings
- Cash received from repayment of loans by borrowers
- Cash paid for operating expenses
(iv) Media Enterprise:
- Cash received from advertisements
- Cash received from subscription fees
- Cash paid to journalists, editors, and other staff
- Cash paid for printing, broadcasting, and distribution expenses
(v) Steel Manufacturing Unit:
- Cash received from sale of steel products
- Cash paid for raw materials (iron ore, coal, etc.)
- Cash paid to workers and employees
- Cash paid for manufacturing overheads, power, and fuel
(vi) Software Development Business Unit:
- Cash received from clients for software development and maintenance contracts
- Cash received from sale of software licences
- Cash paid to software engineers and developers
- Cash paid for hardware, software tools, and other operating expenses
8"The nature/type of enterprise can change altogether the category into which a particular activity may be classified." Do you agree? Illustrate your answer.Show solution
Yes, I fully agree with this statement.
The classification of a cash flow activity depends on the nature of the enterprise. The same activity can fall under different categories for different types of enterprises.
Illustration 1: Interest Received
- For a manufacturing company: Interest received on investments is an Investing Activity (as it is a return on investment, not the main business).
- For a bank or financial institution: Interest received on loans given is an Operating Activity (as lending money and earning interest is the principal business).
Illustration 2: Dividend Received
- For a non-financial company: Dividend received on shares held as investment is an Investing Activity.
- For an investment company: Dividend received is an Operating Activity (as investing in shares and earning dividends is the main business).
Illustration 3: Purchase/Sale of Securities
- For a manufacturing company: Purchase of shares is an Investing Activity.
- For a stock broker or investment company: Purchase and sale of securities is an Operating Activity.
Conclusion: The same transaction can be classified differently depending on the type of enterprise, because what is a primary revenue-generating activity for one enterprise may be a secondary or investment activity for another.
Long Answer Questions
1Describe the procedure to prepare Cash Flow Statement.Show solution
Procedure to Prepare Cash Flow Statement:
A Cash Flow Statement is prepared by analysing the changes in balance sheet items between two accounting periods and the information from the Statement of Profit and Loss.
Step 1: Calculate Cash Flow from Operating Activities (Indirect Method)
- Start with Net Profit before Tax.
- Add back non-cash charges: depreciation, amortisation, provision for doubtful debts, loss on sale of assets.
- Deduct non-operating incomes: profit on sale of assets, dividend received, interest received.
- Adjust for changes in Working Capital:
- Add: Decrease in current assets / Increase in current liabilities
- Deduct: Increase in current assets / Decrease in current liabilities
- Deduct income tax paid → Net Cash from Operating Activities.
Step 2: Calculate Cash Flow from Investing Activities
- Identify all transactions related to purchase/sale of fixed assets and investments.
- Prepare ledger accounts (e.g., Fixed Asset Account, Investment Account) to find actual cash paid/received.
- Include interest received, dividend received (for non-financial enterprises).
- Net of all inflows and outflows → Net Cash from/used in Investing Activities.
Step 3: Calculate Cash Flow from Financing Activities
- Identify transactions related to share capital, debentures, long-term loans.
- Include proceeds from issue of shares/debentures, repayment of loans, payment of dividends, interest paid.
- Net of all inflows and outflows → Net Cash from/used in Financing Activities.
Step 4: Prepare the Cash Flow Statement
Verify: Closing Cash and Cash Equivalents should match the balance sheet figure.
2Describe "Indirect" method of ascertaining Cash Flow from operating activities.Show solution
Indirect Method of Ascertaining Cash Flow from Operating Activities:
Under the Indirect Method, the net profit (or net loss) is adjusted for the effects of:
- Non-cash transactions
- Non-operating items
- Changes in working capital
Format:
| Particulars | Rs. |
|---|---|
| Net Profit before Tax and Extraordinary Items | xxx |
| Add: Non-cash and Non-operating charges: | |
| Depreciation on Fixed Assets | xxx |
| Amortisation of Goodwill/Patents | xxx |
| Loss on Sale of Fixed Assets | xxx |
| Provision for Doubtful Debts | xxx |
| Less: Non-operating incomes: | |
| Profit on Sale of Fixed Assets | (xxx) |
| Interest/Dividend Received (investing) | (xxx) |
| Operating Profit before Working Capital Changes | xxx |
| Add: Decrease in Current Assets | xxx |
| Add: Increase in Current Liabilities | xxx |
| Less: Increase in Current Assets | (xxx) |
| Less: Decrease in Current Liabilities | (xxx) |
| Cash Generated from Operations | xxx |
| Less: Income Tax Paid | (xxx) |
| Net Cash from Operating Activities | xxx |
Key Adjustments Explained:
- Depreciation is added back because it is a non-cash charge that reduced profit but did not involve cash outflow.
- Profit on sale of assets is deducted because it is an investing activity inflow, not operating.
- Increase in debtors is deducted because more goods were sold on credit (cash not received).
- Increase in creditors is added because goods were purchased on credit (cash not paid).
Free with a Super Tutor account
Free with a Super Tutor account
Numerical Questions
Free with a Super Tutor account
| Particulars | Rs. |
|---|---|
| Inventory in the beginning | 40,000 |
| Credit Purchases | 1,60,000 |
| Inventory in the end | 38,000 |
| Trade payables in the beginning | 14,000 |
| Trade payables in the end | 14,500 |
[Ans.: Rs. 1,59,500]
Free with a Super Tutor account
(a) Acquired machinery for Rs. 2,50,000 paying 20% by cheque and executing a bond for the balance payable.
(b) Paid Rs. 2,50,000 to acquire shares in Informa Tech. and received a dividend of Rs. 50,000 after acquisition.
(c) Sold machinery of original cost Rs. 2,00,000 with an accumulated depreciation of Rs. 1,60,000 for Rs. 60,000.
[Ans.: (a) Rs. 50,000 investing activity (outflow); (b) Rs. 2,00,000 investing activity (outflow); (c) Rs. 60,000 investing activity (inflow)]
Free with a Super Tutor account
Statement of Profit and Loss of Yamuna Ltd., for the Year ended March 31, 2017
| Particulars | Note No. | Amount (Rs.) |
|---|---|---|
| i) Revenue from Operations | | 10,00,000 |
| ii) Expenses | | |
| Cost of Materials Consumed | 1 | 50,000 |
| Purchases of Stock-in-trade | | 5,00,000 |
| Other Expenses | 2 | 3,00,000 |
| Total Expenses | | 8,50,000 |
| iii) Profit before tax (i-ii) | | 1,50,000 |
Additional information:
(i) Trade receivables decrease by Rs. 30,000 during the year.
(ii) Prepaid expenses increase by Rs. 5,000 during the year.
(iii) Trade payables increase by Rs. 15,000 during the year.
(iv) Outstanding expenses payable increased by Rs. 3,000 during the year.
(v) Other expenses included depreciation of Rs. 25,000.
Compute net cash from operations for the year ended March 31, 2017 by the indirect method.
[Ans.: Cash from operations Rs. 2,18,000]
Free with a Super Tutor account
(i) Profit for the year 2016-17 is a sum of Rs. 10,000 after providing for depreciation of Rs. 2,000.
(ii) The current assets and current liabilities of the business for the year ended March 31, 2016 and 2017 are as follows:
| Particulars | March 31, 2016 (Rs.) | March 31, 2017 (Rs.) |
|---|---|---|
| Trade Receivables | 14,000 | 15,000 |
| Provision for Doubtful Debts | 1,000 | 1,200 |
| Trade Payables | 13,000 | 15,000 |
| Inventories | 5,000 | 8,000 |
| Other Current Assets | 10,000 | 12,000 |
| Expenses payable | 1,000 | 1,500 |
| Prepaid Expenses | 2,000 | 1,000 |
| Accrued Income | 3,000 | 4,000 |
| Income received in advance | 2,000 | 1,000 |
[Ans.: Cash from operations: Rs. 7,700]
Free with a Super Tutor account
Balance Sheet of Bharat Gas Ltd., as on 31 March, 2016 and 31 March 2017
| Particulars | Note No. | March 31 2017 (Rs.) | March 31 2016 (Rs.) |
|---|---|---|---|
| Fixed assets — Tangible (Machinery) | 1 | 12,40,000 | 10,20,000 |
| Fixed assets — Intangible (Patents) | 2 | 4,60,000 | 3,80,000 |
| Non-current investments | 3 | 3,60,000 | 2,60,000 |
Notes:
1. Tangible Assets — Machinery: 2017: 12,40,000; 2016: 10,20,000
2. Intangible Assets — Goodwill: 2017: 3,00,000; 2016: 1,00,000; Patents: 2017: 1,60,000; 2016: 2,80,000; Total: 2017: 4,60,000; 2016: 3,80,000
3. Non-current Investments — 10% long term investments: 2017: 1,60,000; 2016: 60,000; Investment in land: 2017: 1,00,000; 2016: 1,00,000; Shares of Amartex Ltd.: 2017: 1,00,000; 2016: 1,00,000; Total: 2017: 3,60,000; 2016: 2,60,000
Additional Information:
(a) Patents were written-off to the extent of Rs. 40,000 and some Patents were sold at a profit of Rs. 20,000.
(b) A Machine costing Rs. 1,40,000 (Depreciation provided thereon Rs. 60,000) was sold for Rs. 50,000. Depreciation charged during the year was Rs. 1,40,000.
(c) On March 31, 2016, 10% Investments were purchased for Rs. 1,80,000 and some Investments were sold at a profit of Rs. 20,000. Interest on Investment was received on March 31, 2017.
(d) Amartax Ltd., paid Dividend @ 10% on its shares.
(e) A plot of Land had been purchased for investment purposes and let out for commercial use and rent received Rs. 30,000.
[Ans.: Rs. 5,24,000]
Free with a Super Tutor account
Balance Sheet of Mohan Ltd., as at 31st March 2016 and 31st March 2017
| Particulars | Note No. | March 31, 2017 (Rs.) | March 31, 2016 (Rs.) |
|---|---|---|---|
| Equity share capital | | 3,00,000 | 2,00,000 |
| Reserves and Surplus | | 2,70,000 | 2,20,000 |
| Long-term borrowings (9% Bank Loan) | 1 | 80,000 | 1,00,000 |
| Trade payables | | 1,20,000 | 1,40,000 |
| Total | | 7,70,000 | 6,60,000 |
| Fixed assets (Net) | 2 | 5,00,000 | 3,20,000 |
| Inventories | | 1,50,000 | 1,30,000 |
| Trade receivables | 3 | 90,000 | 1,20,000 |
| Cash and cash equivalents | 4 | 30,000 | 90,000 |
| Total | | 7,70,000 | 6,60,000 |
Notes:
1. Long-term borrowings: 9% Bank Loan: 2017: 80,000; 2016: 1,00,000
2. Fixed assets: Gross: 2017: 6,00,000; 2016: 4,00,000; Accumulated Depreciation: 2017: 1,00,000; 2016: 80,000; Net: 2017: 5,00,000; 2016: 3,20,000
3. Trade receivables: Debtors: 2017: 60,000; 2016: 1,00,000; Bills receivables: 2017: 30,000; 2016: 20,000; Total: 2017: 90,000; 2016: 1,20,000
4. Cash and cash equivalents: Bank: 2017: 30,000; 2016: 90,000
Additional Information:
Machine Costing Rs. 80,000 on which accumulated depreciation was Rs. 50,000 was sold for Rs. 20,000. 9% bank loan Rs. 20,000 was repaid on March 31, 2017. Proposed dividend for the year 2015-16 was Rs. 60,000.
[Ans.: Cash flow from Operating Activities 1,89,000; Cash flow from Investing Activities 2,60,000; Cash flow from Financing Activities 11,000]
Free with a Super Tutor account
Balance Sheet of Tiger Super Steel Ltd. as at 31st March 2014 and 31st March 2017
| Particulars | Note No. | March 31, 2017 (Rs.) | March 31, 2016 (Rs.) |
|---|---|---|---|
| Share capital | 1 | 1,40,000 | 1,20,000 |
| Reserves and surplus | 2 | 38,400 | 26,400 |
| Trade payables (Bills payable) | 3 | 21,200 | 14,000 |
| Other current liabilities (Outstanding expenses) | 4 | 2,400 | 3,200 |
| Short-term provisions (Provision for taxation) | 5 | 12,800 | 11,200 |
| Total | | 2,14,800 | 1,74,800 |
| Tangible assets | 6 | 96,400 | 76,000 |
| Intangible assets | | 18,800 | 24,000 |
| Non-current investments | | 14,000 | 4,000 |
| Inventories | | 31,200 | 34,000 |
| Trade receivables | | 43,200 | 30,000 |
| Cash and Cash Equivalents | | 11,200 | 6,800 |
| Total | | 2,14,800 | 1,74,800 |
Notes:
1. Share Capital: Equity: 2017: 1,20,000; 2016: 80,000; 10% Preference: 2017: 20,000; 2016: 40,000
2. Reserves and surplus: General reserve: 2017: 12,000; 2016: 8,000; Balance in P&L: 2017: 26,400; 2016: 18,400
3. Bills payable: 2017: 21,200; 2016: 14,000
4. Outstanding expenses: 2017: 2,400; 2016: 3,200
5. Provision for taxation: 2017: 12,800; 2016: 11,200
6. Tangible assets: Land and building: 2017: 20,000; 2016: 40,000; Plant: 2017: 76,400; 2016: 36,000
Additional Information:
Proposed dividend for 2016-17 is Rs. 15,600 and for 2015-16 is Rs. 11,200.
Depreciation Charged on Land & Building Rs. 20,000, and Plant Rs. 10,000 during the year.
[Ans.: Cash flow from Operating Activities Rs. 56,000; Cash flow from Investing Activities Rs. 60,400; Cash flow from Financing Activities Rs. 8,800]
Free with a Super Tutor account
| Particulars | Note No. | 31st March 2015 (Rs.) | 31st March 2014 (Rs.) |
|---|---|---|---|
| Share capital | | 7,00,000 | 5,00,000 |
| Reserve and surplus | | 4,70,000 | 2,50,000 |
| 8% Debentures | | 4,00,000 | 6,00,000 |
| Trade payables | | 9,00,000 | 6,00,000 |
| Total | | 24,70,000 | 19,50,000 |
| Tangible Fixed assets | | 7,00,000 | 5,00,000 |
| Intangible — Goodwill | | 1,70,000 | 2,50,000 |
| Inventories | | 6,00,000 | 5,00,000 |
| Trade Receivables | | 6,00,000 | 4,00,000 |
| Cash and cash equivalents | | 4,00,000 | 3,00,000 |
| Total | | 24,70,000 | 19,50,000 |
Additional Information:
Depreciation Charged on Plant amounted to Rs. 80,000.
[Ans.: Cash inflow from Operating Activities 4,28,000; Cash inflow from Investing Activities 2,80,000; Cash inflow from Financing Activities 48,000]
Free with a Super Tutor account
| Particulars | Note No. | 31st March 2017 (Rs.) | 31st March 2016 (Rs.) |
|---|---|---|---|
| Equity share capital | | 3,00,000 | 2,00,000 |
| Preference share capital | | 1,00,000 | — |
| Reserve and surplus (Surplus) | | 2,00,000 | 1,00,000 |
| 8% Long-term loan | | — | 2,00,000 |
| 9% Loan from Rahul | | 1,50,000 | 20,000 |
| Bank overdraft | | 1,00,000 | — |
| Trade payables | | 70,000 | 50,000 |
| Provision for taxation | | 50,000 | 30,000 |
| Total | | 9,70,000 | 6,00,000 |
| Tangible Fixed assets | | 7,00,000 | 4,00,000 |
| Inventories | | 1,70,000 | 1,00,000 |
| Trade Receivables | | 1,00,000 | 50,000 |
| Cash and cash equivalents | | — | 50,000 |
| Total | | 9,70,000 | 6,00,000 |
Additional Information:
Net Profit for the year after charging Rs. 50,000 as Depreciation was Rs. 1,50,000. Dividend paid on Share was Rs. 50,000. Tax Provision created during the year amounted to Rs. 60,000. 8% loan was repaid on March 31, 2017 and an additional 9% loan of Rs. 1,30,000 was obtained from Rahul on April 01, 2016.
[Ans.: Cash from Operating Activities 1,49,500; Cash from Investing Activities 13,50,000; Cash from Financing Activities 1,50,000]
Free with a Super Tutor account
| Particulars | Note No. | 31st March 2017 (Rs.) | 31st March 2016 (Rs.) |
|---|---|---|---|
| Equity share capital | | 3,00,000 | 2,00,000 |
| Preference share capital | | 1,40,000 | 80,000 |
| Reserve and surplus (Surplus) | 2 | 40,000 | 28,000 |
| Trade payables | | 1,56,000 | 56,000 |
| Provision for taxation | | 12,000 | 4,000 |
| Total | | 6,48,000 | 3,68,000 |
| Tangible Fixed assets | | 3,64,000 | 2,00,000 |
| Inventories | | 1,60,000 | 60,000 |
| Trade receivables | | 80,000 | 20,000 |
| Cash and cash equivalents | | 28,000 | 80,000 |
| Other current assets (prepaid expenses) | | 16,000 | 8,000 |
| Total | | 6,48,000 | 3,68,000 |
Notes:
2. Reserve and surplus:
Surplus at beginning: 28,000
Add: Profit of the year: 16,000
Less: Interim Dividend: 4,000
Profit at end: 40,000
Additional Information:
1. Depreciation charged during the year Rs. 32,000
[Ans.: Cash flow from Operating Activities 12,000; Cash flow from Investing Activities 1,96,000; Cash flow from Financing Activities 1,56,400]
Free with a Super Tutor account
| Particulars | Note No. | 31st March 2017 | 31st March 2016 |
|---|---|---|---|
| Share capital | | 52,000 | 40,000 |
| Reserve and surplus-Surplus | 1 | 9,500 | 8,000 |
| 10% Debentures | | 6,500 | 6,000 |
| Bank overdraft | 2 | 6,800 | 12,500 |
| Trade payables | 3 | 11,000 | 12,000 |
| Short-term provisions (Provision for taxation) | | 4,200 | 3,000 |
| Total | | 90,000 | 81,500 |
| Fixed Assets (Net) | 4 | 27,000 | 30,000 |
| Inventories | | 35,000 | 30,000 |
| Trade receivables | | 24,000 | 20,000 |
| Cash | | 3,500 | 1,200 |
| Prepaid expenses | | 500 | 300 |
| Total | | 90,000 | 81,500 |
Notes:
1. Reserve and surplus: Balance in P&L: 2017: 7,000; 2016: 6,000; General reserve: 2017: 2,500; 2016: 2,000
2. Bank overdraft: 2017: 6,800; 2016: 12,500
3. Short-term provisions: Provision for taxation: 2017: 4,200; 2016: 3,000
4. Fixed Assets: Gross: 2017: 42,000; 2016: 41,000; Accumulated Depreciation: 2017: 15,000; 2016: 11,000; Net: 2017: 27,000; 2016: 30,000
Additional Information:
Proposed dividend for the year 2015-16 is Rs. 2,50,00,000
[Ans.: Net Cash from Operating Activities Rs. 2,100; Net Cash from Investing Activities Rs. 1,000; Net Cash from Financing Activities Rs. 4,900] (All figures in Rs. '000)
Free with a Super Tutor account
14 more solved questions in Cash Flow Statement
They are free with a Super Tutor account, along with practice quizzes and flashcards for this chapter. Free to start, no card needed.
Frequently Asked Questions
What are the important topics in Cash Flow Statement for Madhya Pradesh Board Class 12 Accountancy?
Are these NCERT Solutions for Cash Flow Statement free?
How should I revise Cash Flow Statement for the Madhya Pradesh Board Class 12 board exam?
Sources & Official References
Content is aligned to the official syllabus. Refer to the board website for the latest curriculum.
More resources for Cash Flow Statement
Practice Quiz
Test yourself with a quick quiz
Important Questions
Exam-style questions with answers
Revision Notes
Key points for last-minute revision
Formula Sheet
The chapter's formulas in one place
Chapter Summary
Understand the chapter at a glance
Concept Maps
See how topics connect
Study Plan
Step-by-step plan for this chapter
Flashcards
Quick-fire cards for active recall
Syllabus
What topics to cover
For serious students
Get the full Cash Flow Statement chapter — start free.
Quizzes, flashcards, an AI doubt solver and a study plan for Madhya Pradesh Board Class 12 Accountancy. Free to start, no card needed.