Dissolution of Partnership Firm — NCERT Solutions
Madhya Pradesh Board · Class 12 · Accountancy
NCERT Solutions for Dissolution of Partnership Firm, Madhya Pradesh Board Class 12 Accountancy: 64 textbook questions solved step by step.
Interactive on Super Tutor
Studying Dissolution of Partnership Firm? Get the full interactive chapter.
Quizzes, flashcards, AI doubt-solver and a step-by-step study plan — built for NCERT solutions and more.
Free trial, no card needed.
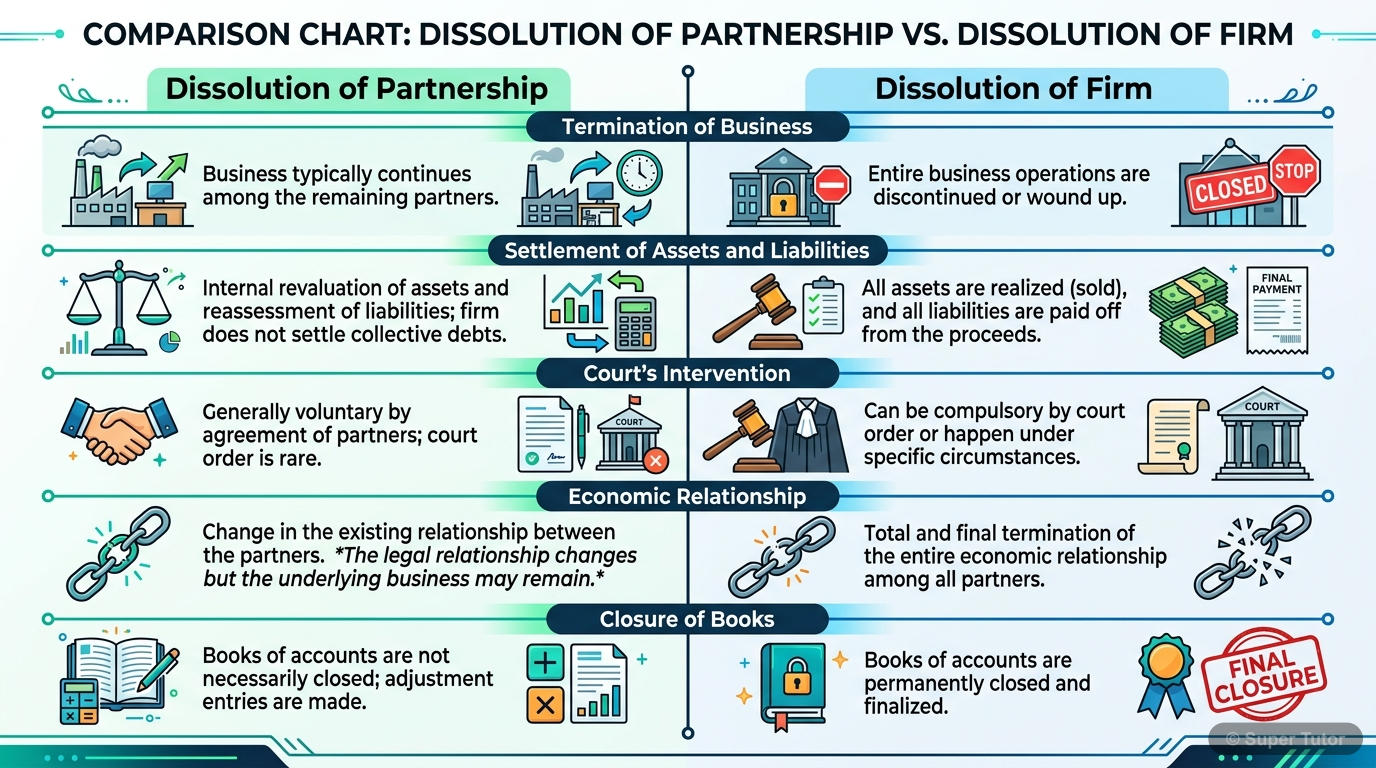
Learn better with visuals Super Tutor pairs illustrations like this with notes and quizzes for Dissolution of Partnership Firm.
The first 32 solutions are open to read. The other 32 are free with a Super Tutor account.
Test your Understanding - I
1Dissolution of a partnership is different from dissolution of a firm.Show solution
TRUE. Dissolution of partnership means a change in the existing relationship among partners (e.g., due to admission, retirement, death), but the firm continues its business. Dissolution of a firm, on the other hand, means complete closure of the firm's business, realisation of all assets and settlement of all liabilities. Thus, the two are distinct concepts.
2A partnership is dissolved when there is a death of a partner.Show solution
TRUE. On the death of a partner, the existing partnership (i.e., the agreement among the existing set of partners) comes to an end. However, the remaining partners may continue the business by forming a new partnership, so the firm need not necessarily be dissolved. Hence, death of a partner leads to dissolution of partnership, not necessarily dissolution of the firm.
3A firm is dissolved when all partners give consent to it.Show solution
TRUE. Under the Indian Partnership Act, a firm can be dissolved by mutual consent of all the partners. When all partners agree to dissolve the firm, it is called dissolution by agreement, and the firm is dissolved.
4A firm is compulsorily dissolved when a partner decides to retire.Show solution
FALSE. Retirement of a partner leads to dissolution of partnership (the existing agreement changes), not compulsory dissolution of the firm. The remaining partners can continue the business. Compulsory dissolution occurs in specific situations such as when all partners (or all but one) become insolvent, or when the business becomes unlawful.
5Dissolution of a firm necessarily involves dissolution of partnership.Show solution
TRUE. When a firm is dissolved, the business is completely closed and all economic relationships among partners come to an end. This necessarily means the partnership (the agreement among partners) is also dissolved. However, the converse is not true — dissolution of partnership does not necessarily mean dissolution of the firm.
6A firm is compulsorily dissolved when all partners or when all except one partner become insolvent.Show solution
TRUE. Under the Indian Partnership Act, a firm is compulsorily dissolved when all the partners, or all the partners except one, are adjudicated insolvent. In such a case, the firm cannot carry on business and is compulsorily dissolved by operation of law.
7Court can order a firm to be dissolved when a partner becomes insane.Show solution
TRUE. Under Section 44 of the Indian Partnership Act, a court may order dissolution of a firm when a partner has become of unsound mind (insane). The court exercises its discretion and may dissolve the firm on an application by any partner or the next friend of the insane partner.
8Dissolution of partnership cannot take place without intervention of the court.Show solution
FALSE. Dissolution of partnership can take place without the intervention of the court. It can occur by mutual agreement among partners, by expiry of the term of partnership, by completion of the venture, by retirement or death of a partner, etc. Court intervention is required only in specific cases of dissolution of the firm (not partnership) under Section 44 of the Indian Partnership Act.
Test your Understanding - II
1On dissolution of a firm, bank overdraft is transferred to:
(a) Cash Account
(b) Bank Account
(c) Realisation Account
(d) Partner's Capital Account.Show solution
Correct Answer: (c) Realisation Account.
Justification: On dissolution, all external liabilities (including bank overdraft) are transferred to the Realisation Account (Credit side). The bank overdraft is a liability of the firm and is therefore credited to the Realisation Account when transferred.
2On dissolution of a firm, partner's loan account is transferred to:
(a) Realisation Account
(b) Partner's Capital Account
(c) Partner's Current Account
(d) None of the above.Show solution
Correct Answer: (d) None of the above.
Justification: Partner's loan is not transferred to the Realisation Account (as it is not a third-party liability in the usual sense) nor to the Capital Account directly. It is paid off separately from the Bank Account after all external liabilities are settled but before the partners' capitals are returned. Hence, none of the given options (a), (b), or (c) is correct.
3After transferring liabilities like creditors and bills payables in the Realisation Account, in the absence of any information regarding their payment, such liabilities are treated as:
(a) Never paid
(b) Fully paid
(c) Partly paid
(d) None of the above.Show solution
Correct Answer: (b) Fully paid.
Justification: In the absence of any specific information about the settlement of liabilities (creditors, bills payable, etc.) that have been transferred to the Realisation Account, it is assumed that they are paid in full. The Bank Account is credited with the full amount of such liabilities.
4When realisation expenses are paid by the firm on behalf of a partner, such expenses are debited to:
(a) Realisation Account
(b) Partner's Capital Account
(c) Partner's Loan Account
(d) None of the above.Show solution
Correct Answer: (b) Partner's Capital Account.
Justification: When realisation expenses are to be borne by a particular partner (i.e., the partner is responsible for them) but are paid by the firm, the amount is debited to that Partner's Capital Account (since it is a personal expense of the partner paid by the firm on his/her behalf). The Realisation Account is not debited in this case.
5Unrecorded assets when taken over by a partner are shown in:
(a) Debit of Realisation Account
(b) Debit of Bank Account
(c) Credit of Realisation Account
(d) Credit of Bank Account.Show solution
Correct Answer: (c) Credit of Realisation Account.
Justification: When an unrecorded asset is taken over by a partner, the entry is:
Debit: Partner's Capital Account
Credit: Realisation Account
The Realisation Account is credited because the asset (though unrecorded) is being realised (taken over) at the agreed value, which represents a gain/receipt for the firm.
6Unrecorded liabilities when paid are shown in:
(a) Debit of Realisation Account
(b) Debit of Bank Account
(c) Credit of Realisation Account
(d) Credit of Bank Account.Show solution
Correct Answer: (a) Debit of Realisation Account.
Justification: When an unrecorded liability is paid, the entry is:
Debit: Realisation Account
Credit: Bank Account
The Realisation Account is debited because payment of an unrecorded liability is an additional loss/expense at the time of dissolution.
7The accumulated profits and reserves are transferred to:
(a) Realisation Account
(b) Partners' Capital Accounts
(c) Bank Account
(d) None of the above.Show solution
Correct Answer: (b) Partners' Capital Accounts.
Justification: Accumulated profits, reserves (like General Reserve, Profit & Loss Account credit balance, Workmen Compensation Reserve, etc.) are not transferred to the Realisation Account. They are transferred directly to the Partners' Capital Accounts in their profit-sharing ratio, as these belong to the partners.
8On dissolution of the firm, partner's capital accounts are closed through:
(a) Realisation Account
(b) Drawings Account
(c) Bank Account
(d) Loan Account.Show solution
Correct Answer: (c) Bank Account.
Justification: After all assets are realised and liabilities are paid off, the final balance in each Partner's Capital Account (whether debit or credit) is settled through the Bank Account. If a partner is owed money, Bank Account is credited and Capital Account is debited; if a partner owes money, Bank Account is debited and Capital Account is credited.
Test your Understanding - III
1All assets (except cash/bank and fictitious assets) are transferred to the ________ (Debit/Credit) side of ________ Account (Realisation/Capital).Show solution
All assets (except cash/bank and fictitious assets) are transferred to the Debit side of Realisation Account.
Reason: On dissolution, all real assets (other than cash/bank, which are kept separately, and fictitious assets which are written off to Capital Accounts) are transferred to the debit side of the Realisation Account at their book values.
2All ________ (internal/external) liabilities are transferred to the ________ (Debit/Credit) side of ________ account (Bank/Realisation).Show solution
All external liabilities are transferred to the Credit side of Realisation Account.
Reason: External liabilities (creditors, bills payable, bank overdraft, etc.) are obligations to third parties. On dissolution, they are credited to the Realisation Account. Internal liabilities (like partners' loans, capitals) are not transferred to the Realisation Account.
3Accumulated losses are transferred to ________ (Realisation/Capital Accounts) in ________ (equal ratio/profit sharing ratio).Show solution
Accumulated losses are transferred to Capital Accounts in profit sharing ratio.
Reason: Accumulated losses (like debit balance of Profit & Loss Account, fictitious assets) are losses belonging to the partners and are therefore transferred to their Capital Accounts in their profit-sharing ratio.
4If a liability is assumed by a partner, such Partner's Capital Account is ________ (debited/credited).Show solution
If a liability is assumed by a partner, such Partner's Capital Account is credited.
Reason: When a partner agrees to discharge a firm's liability personally, the firm is relieved of that liability. The partner's Capital Account is credited (as the partner is effectively paying on behalf of the firm, which is a benefit/credit to the firm from that partner's side — the Realisation Account is debited and Partner's Capital Account is credited).
5If a partner takes over an asset, such (Partner's Capital Account) is ________ (debited/credited).Show solution
If a partner takes over an asset, such Partner's Capital Account is debited.
Reason: When a partner takes over an asset of the firm, the partner owes the agreed value to the firm. Therefore, the Partner's Capital Account is debited (and Realisation Account is credited) with the agreed value of the asset taken over.
6No entry is required when a ________ (partner/creditor) accepts a fixed asset in payment of his dues.Show solution
No entry is required when a creditor accepts a fixed asset in payment of his dues.
Reason: When a creditor accepts a fixed asset in full settlement of his dues, both the asset and the liability have already been transferred to the Realisation Account. Since both sides of the Realisation Account are already affected, no separate entry is needed — the effect is automatically captured.
7When creditor accepts an asset whose value is much more than the amount due to him, he will —— (pay/not pay) the excess amount which will be credited —— Account.Show solution
When a creditor accepts an asset whose value is much more than the amount due to him, he will pay the excess amount which will be credited to Realisation Account.
Reason: If the asset's value exceeds the creditor's claim, the creditor must pay the difference to the firm. This excess amount received is credited to the Realisation Account as it represents a gain on realisation.
Journal Entry:
8When the firm has agreed to pay the partner a fixed amount for realisation work irrespective of the actual amount spent, such fixed amount is debited to (Realisation/Capital) Account and Credited to (Capital/Bank) Account.Show solution
Such fixed amount is debited to Realisation Account and credited to Capital Account.
Reason: When a partner is appointed to carry out realisation work and is to be paid a fixed remuneration (commission), this is an expense of realisation for the firm. Hence, Realisation Account is debited and the concerned Partner's Capital Account is credited with the fixed amount agreed upon (irrespective of actual expenses incurred by the partner).
9Partner's loan is —— (transferred/not transferred) in the (Realisation Account).Show solution
Partner's loan is not transferred to the Realisation Account.
Reason: Partner's loan is an internal liability (owed to a partner, not to a third party). It is not transferred to the Realisation Account. It is paid off separately from the Bank Account after all external liabilities are settled but before the partners' capitals are returned.
10Partner's current accounts are transferred to respective —— Partners' (Loan/Capital) Accounts.Show solution
Partner's current accounts are transferred to respective Partners' Capital Accounts.
Reason: On dissolution of the firm, the balances in Partners' Current Accounts (whether debit or credit) are transferred to the respective Partners' Capital Accounts so that a single account reflects the net amount due to or from each partner.
Do it Yourself
1Give the journal entry for closure of assets accounts on dissolution of a partnership firm.Show solution
Given: On dissolution, all assets (except cash/bank and fictitious assets) are transferred to the Realisation Account.
Journal Entry:
(Being all assets transferred to Realisation Account at book value)
Note: Cash/Bank Account is not transferred. Fictitious assets (like Profit & Loss debit balance, Preliminary Expenses) are transferred to Partners' Capital Accounts in profit-sharing ratio, not to Realisation Account.
2Give the journal entry for closure of liabilities accounts on dissolution of a partnership firm.Show solution
Given: On dissolution, all external liabilities are transferred to the Realisation Account.
Journal Entry:
(Being all external liabilities — creditors, bills payable, bank overdraft, etc. — transferred to Realisation Account)
Note: Partners' loan accounts and partners' capital accounts are NOT transferred to the Realisation Account.
3Give the journal entry for sale of assets on dissolution of a partnership firm.Show solution
Given: Assets are sold for cash on dissolution.
Journal Entry:
(Being assets sold and proceeds credited to Realisation Account)
4Give the journal entry for settlement of a creditor by transfer of fixed assets to him on dissolution of a partnership firm.Show solution
Given: A creditor accepts a fixed asset in full/part settlement of his dues. Both the asset and the creditor's liability have already been transferred to the Realisation Account.
No separate journal entry is required in this case, because:
- The asset has already been debited to Realisation Account.
- The creditor's liability has already been credited to Realisation Account.
- Both sides are already recorded; the transfer of asset to creditor is merely a settlement within the Realisation Account.
However, if the asset's value differs from the creditor's claim:
- If asset value > creditor's claim: Creditor pays the excess to the firm.
- If asset value < creditor's claim: Firm pays the balance in cash.
5Give the journal entry for expenses of realisation when actual expenses are paid by the partner on behalf of the firm on dissolution.Show solution
Given: Realisation expenses are paid by a partner personally on behalf of the firm.
Journal Entry:
(Being realisation expenses paid by the partner on behalf of the firm, credited to his Capital Account)
Explanation: Since the partner has paid the firm's expenses from his own pocket, the firm owes this amount to the partner. Hence, the partner's Capital Account is credited and Realisation Account is debited.
6Give the journal entry when a partner discharges the liability of the firm on dissolution.Show solution
Given: A partner agrees to pay off a firm's liability (e.g., a creditor or loan) personally.
Journal Entry:
(Being firm's liability discharged by the partner; partner's Capital Account credited)
Explanation: When a partner takes over a liability, the Realisation Account is debited (as the liability was already credited to Realisation Account when transferred, this entry effectively cancels it) and the Partner's Capital Account is credited, since the partner is bearing the liability on behalf of the firm.
Free with a Super Tutor account
Free with a Super Tutor account
Short Answer Questions
Free with a Super Tutor account
Free with a Super Tutor account
Free with a Super Tutor account
Free with a Super Tutor account
Free with a Super Tutor account
Free with a Super Tutor account
Long Answer Questions
Free with a Super Tutor account
Free with a Super Tutor account
Free with a Super Tutor account
Free with a Super Tutor account
Numerical Questions
[a] Realisation expenses amounted to Rs.2,500.
[b] Realisation expenses amounting to Rs.3,000 were paid by Ashok, one of the partners.
[c] Realisation expenses Rs.2,300 borne by Tarun, personally.
[d] Amit, a partner was appointed to realise the assets, at a cost of Rs.4,000. The actual amount of realisation expenses amounted to Rs.3,000.
Free with a Super Tutor account
[a] Creditors worth Rs.85,000 accepted Rs.40,000 as cash and Investment worth Rs.43,000, in full settlement of their claim.
[b] Creditors were Rs.16,000. They accepted Machinery valued at Rs.18,000 in settlement of their claim.
[c] Creditors were Rs.90,000. They accepted Buildings valued Rs.1,20,000 and paid cash to the firm Rs.30,000.
Free with a Super Tutor account
Free with a Super Tutor account
[a] Payment of unrecorded liabilities of Rs.3,200.
[b] Stock worth Rs.7,500 is taken over by a partner Rohit.
[c] Profit on Realisation amounting to Rs.18,000 is to be distributed between the partners Ashish and Tarun in the ratio of 5:7.
[d] An unrecorded asset realised Rs.5,500.
Free with a Super Tutor account
1. To record the realisation of various assets and liabilities.
2. A Firm has a Stock of Rs.1,60,000. Aziz, a partner took over 50% of the Stock at a discount of 20%.
3. Remaining Stock was sold at a profit of 30% on cost.
4. Land and Building (book value Rs.1,60,000) sold for Rs.3,00,000 through a broker who charged 2% commission on the deal.
5. Plant and Machinery (book value Rs.60,000) was handed over to a Creditor at an agreed valuation of 10% less than the book value.
6. Investment whose face value was Rs.4,000 was realised at 50%.
Free with a Super Tutor account
1. Realisation expenses amount to Rs.1,00,000.
2. Realisation expenses amounting to Rs.30,000 are paid by Rashim, a partner.
3. Realisation expenses are to be borne by Rashim and he will be paid Rs.70,000 as remuneration for completing the dissolution process. The actual expenses incurred by Rashim were Rs.1,20,000.
Free with a Super Tutor account
Free with a Super Tutor account
1. There was an old furniture in the firm which had been written-off completely in the books. This was sold for Rs.3,000.
2. Ashish, an old customer whose account for Rs.1,000 was written-off as bad in the previous year, paid 60% of the amount.
3. Paras agreed to takeover the firm's goodwill (not recorded in the books of the firm), at a valuation of Rs.30,000.
4. There was an old typewriter which had been written-off completely from the books. It was estimated to realise Rs.400. It was taken away by Priya at an estimated price less 25%.
5. There were 100 shares of Rs.10 each in Star Limited acquired at a cost of Rs.2,000 which had been written-off completely from the books. These shares are valued @ Rs.6 each and divided among the partners in their profit sharing ratio.
Free with a Super Tutor account
Free with a Super Tutor account
1. Arti took over the Stock worth Rs.80,000 at Rs.68,000.
2. There was unrecorded Bike of Rs.40,000 which was taken over by Mr. Karim.
3. The firm paid Rs.40,000 as compensation to employees.
4. Sundry creditors amounting to Rs.36,000 were settled at a discount of 15%.
5. Loss on realisation Rs.42,000 was to be distributed between Arti and Karim in the ratio of 3:4.
Free with a Super Tutor account
Liabilities: Creditors Rs.40,000; Lily's loan Rs.32,000; Profit and Loss Rs.50,000; Lily's Capital Rs.1,60,000; Rose's Capital Rs.2,40,000. Total Rs.5,22,000.
Assets: Cash Rs.16,000; Debtors Rs.80,000 less Provision Rs.3,600 = Rs.76,400; Inventory Rs.1,09,600; Bills receivable Rs.40,000; Buildings Rs.2,80,000. Total Rs.5,22,000.
Rose and Lily decided to dissolve the firm on the above date. Assets (except bills receivables) realised Rs.4,84,000. Creditors agreed to take Rs.38,000. Cost of realisation was Rs.2,400. There was a Motor Cycle in the firm which was bought out of the firm's money, was not shown in the books of the firm. It was now sold for Rs.10,000. There was a contingent liability in respect of outstanding electric bill of Rs.5,000 which was paid. Bill Receivable taken over by Rose at Rs.33,000.
Show Realisation Account, Partners Capital Account, Loan Account and Cash Account.
Free with a Super Tutor account
Liabilities: Shilpa's Capital Rs.80,000; Meena's Capital Rs.40,000; Bank loan Rs.20,000; Creditors Rs.37,000; Provision for doubtful debts Rs.1,200; General reserve Rs.12,000. Total Rs.1,90,200.
Assets: Land Rs.81,000; Stock Rs.56,760; Debtors Rs.18,600; Nanda's capital (debit) Rs.23,000; Cash Rs.10,840. Total Rs.1,90,200.
The stock of value Rs.41,660 are taken over by Shilpa for Rs.35,000 and she agreed to discharge bank loan. The remaining stock was sold at Rs.14,000 and debtors amounting to Rs.10,000 realised Rs.8,000. Land is sold for Rs.1,10,000. The remaining debtors realised 50% at their book value. Cost of realisation amounted to Rs.1,200. There was a typewriter not recorded in the books worth Rs.6,000 which were taken over by one of the Creditors at this value. Prepare Realisation Account.
Free with a Super Tutor account
Liabilities: Creditors Rs.38,000; Mrs. Surjit loan Rs.10,000; Reserve Rs.15,000; Rahi's loan Rs.5,000; Surjit's Capital Rs.10,000; Rahi's Capital Rs.8,000. Total Rs.86,000.
Assets: Bank Rs.11,500; Stock Rs.6,000; Debtors Rs.19,000; Furniture Rs.4,000; Plant Rs.28,000; Investment Rs.10,000; Profit and Loss Rs.7,500. Total Rs.86,000.
The firm was dissolved on March 31, 2017 on the following terms:
1. Surjit agreed to take the investments at Rs.8,000 and to pay Mrs. Surjit's loan.
2. Other assets were realised as follows: Stock Rs.5,000; Debtors Rs.18,500; Furniture Rs.4,500; Plant Rs.25,000.
3. Expenses on realisation amounted to Rs.1,600.
4. Creditors agreed to accept Rs.37,000 as a final settlement.
Prepare Realisation account, Partner's Capital account and Bank account.
Free with a Super Tutor account
Liabilities: Rita Rs.80,000; Geeta Rs.50,000; Ashish Rs.30,000 = Rs.1,60,000; Creditors Rs.65,000; Bills payable Rs.26,000; General reserve Rs.20,000. Total Rs.2,71,000.
Assets: Cash Rs.22,500; Debtors Rs.52,300; Stock Rs.36,000; Investments Rs.69,000; Plant Rs.91,200. Total Rs.2,71,000.
On dissolution:
1. Rita was appointed to realise the assets. Rita was to receive 5% commission on the sale of assets (except cash) and was to bear all expenses of realisation.
2. Assets were realised as follows: Debtors Rs.30,000; Stock Rs.26,000; Plant Rs.42,750.
3. Investments were realised at 85% of the book value.
4. Expenses of realisation amounted to Rs.4,100.
5. Firm had to pay Rs.7,200 for outstanding salary not provided for earlier.
6. Contingent liability in respect of bills discounted with the bank was also materialised and paid off Rs.9,800.
Prepare Realisation account, Capital Accounts of Partners and Cash Account.
Free with a Super Tutor account
Liabilities: Sundry Creditors Rs.27,000; General Reserve Rs.10,000; Loan Rs.40,000; Anup's Capital Rs.60,000; Sumit's Capital Rs.60,000. Total Rs.1,97,000.
Assets: Cash at bank Rs.11,000; Sundry Debtors Rs.12,000; Plants Rs.47,000; Stock Rs.42,000; Lease hold land Rs.60,000; Furniture Rs.25,000. Total Rs.1,97,000.
Assets realised: Lease hold land Rs.72,000; Furniture Rs.22,500; Stock Rs.40,500; Plant Rs.48,000; Sundry Debtors Rs.10,500.
Creditors paid Rs.25,500 in full settlement. Expenses of realisation Rs.2,500.
Prepare Realisation Account, Bank Account, Partners Capital Accounts to close the books of the firm.
Free with a Super Tutor account
Liabilities: Ashu's Capital Rs.1,08,000; Harish's Capital Rs.54,000; Creditors Rs.88,000; Bank overdraft Rs.50,000. Total Rs.3,00,000.
Assets: Building Rs.80,000; Machinery Rs.70,000; Furniture Rs.14,000; Stock Rs.20,000; Investments Rs.60,000; Debtors Rs.48,000; Cash in hand Rs.8,000. Total Rs.3,00,000.
Ashu takes over Building at Rs.95,000. Machinery and Furniture taken over by Harish at Rs.80,000. Ashu agreed to pay Creditors and Harish agreed to meet Bank overdraft. Stock and Investments taken by both partners in profit sharing ratio. Debtors realised Rs.46,000. Expenses of realisation Rs.3,000.
Prepare necessary ledger accounts.
Free with a Super Tutor account
Liabilities: Sanjay Rs.1,00,000; Tarun Rs.1,00,000; Vineet Rs.70,000; Creditors Rs.80,000; Bills payable Rs.30,000. Total Rs.3,80,000.
Assets: Plant Rs.90,000; Debtors Rs.60,000; Furniture Rs.32,000; Stock Rs.60,000; Investments Rs.70,000; Bills receivable Rs.36,000; Cash in hand Rs.32,000. Total Rs.3,80,000.
Sanjay was appointed to realise the assets. Sanjay was to receive 6% commission on the sale of assets (except cash) and was to bear all expenses of realisation.
Sanjay realised: Plant Rs.72,000; Debtors Rs.54,000; Furniture Rs.18,000; Stock 90% of book value; Investments Rs.76,000; Bills receivable Rs.31,000. Expenses of realisation Rs.4,500.
Prepare Realisation Account, Capital Accounts and Cash Account.
Free with a Super Tutor account
Liabilities: Sundry Creditors Rs.38,000; Mrs. Gupta's loan Rs.20,000; Mrs. Sharma's loan Rs.30,000; General Reserve Rs.6,000; Provision for doubtful debts Rs.4,000; Gupta's Capital Rs.90,000; Sharma's Capital Rs.60,000. Total Rs.2,48,000.
Assets: Cash at bank Rs.12,500; Sundry Debtors Rs.55,000; Stock Rs.44,000; Bills receivable Rs.19,000; Machinery Rs.52,000; Investment Rs.38,500; Fixtures Rs.27,000. Total Rs.2,48,000.
Dissolved on December 31, 2017:
(a) Assets realised: Sundry Debtors Rs.52,000; Stock Rs.42,000; Bills receivable Rs.16,000; Machinery Rs.49,000; Fixtures Rs.20,000.
(b) Investment taken over by Gupta at Rs.36,000 and agreed to pay Mrs. Gupta's loan.
(c) Sundry Creditors paid off less 3% discount.
(d) Realisation expenses Rs.1,200.
Journalise the entries and prepare Realisation Account, Bank Account and Partners Capital Accounts.
Free with a Super Tutor account
Liabilities: Sundry Creditors Rs.20,000; Bills payable Rs.25,500; Chetan's loan Rs.30,000; Ashok's Capital Rs.70,000; Babu's Capital Rs.55,000; Chetan's Capital Rs.27,000; Current Accounts: Ashok Rs.10,000; Babu Rs.5,000; Chetan Rs.3,000. Total Rs.2,45,500.
Assets: Bank Rs.7,500; Sundry Debtors Rs.58,000; Stock Rs.39,500; Machinery Rs.48,000; Investment Rs.42,000; Freehold property Rs.50,500. Total Rs.2,45,500.
Machinery taken over by Babu for Rs.45,000; Investment taken over by Ashok for Rs.40,000; Freehold property taken over by Chetan at Rs.55,000. Remaining assets realised: Sundry Debtors Rs.56,500; Stock Rs.36,500. Creditors settled at 7% discount. Office computer (unrecorded) realised Rs.9,000. Realisation expenses Rs.3,000.
Prepare Realisation Account, Partners Capital Account, Bank Account.
Free with a Super Tutor account
Liabilities: Sundry Creditors Rs.62,000; Bills payable Rs.32,000; Bank loan Rs.50,000; General Reserve Rs.16,000; Tanu's Capital Rs.1,10,000; Manu's Capital Rs.90,000. Total Rs.3,60,000.
Assets: Cash at bank Rs.16,000; Sundry Debtors Rs.55,000; Stock Rs.75,000; Motor car Rs.90,000; Machinery Rs.45,000; Investment Rs.70,000; Fixtures Rs.9,000. Total Rs.3,60,000.
Tanu agrees to pay bank loan and took away sundry debtors. Sundry creditors accept stock and paid Rs.10,000 to the firm. Machinery taken over by Manu for Rs.40,000 and agreed to pay bills payable at 5% discount. Motor car taken over by Tanu for Rs.60,000. Investment realised Rs.76,000 and fixtures Rs.4,000. Expenses of dissolution Rs.2,200.
Prepare Realisation Account, Bank Account and Partners Capital Accounts.
Free with a Super Tutor account
32 more solved questions in Dissolution of Partnership Firm
They are free with a Super Tutor account, along with practice quizzes and flashcards for this chapter. Free to start, no card needed.
Frequently Asked Questions
What are the important topics in Dissolution of Partnership Firm for Madhya Pradesh Board Class 12 Accountancy?
Are these NCERT Solutions for Dissolution of Partnership Firm free?
How should I revise Dissolution of Partnership Firm for the Madhya Pradesh Board Class 12 board exam?
Sources & Official References
Content is aligned to the official syllabus. Refer to the board website for the latest curriculum.
More resources for Dissolution of Partnership Firm
Practice Quiz
Test yourself with a quick quiz
Important Questions
Exam-style questions with answers
Revision Notes
Key points for last-minute revision
Formula Sheet
The chapter's formulas in one place
Chapter Summary
Understand the chapter at a glance
Concept Maps
See how topics connect
Study Plan
Step-by-step plan for this chapter
Flashcards
Quick-fire cards for active recall
Syllabus
What topics to cover
For serious students
Get the full Dissolution of Partnership Firm chapter — start free.
Quizzes, flashcards, an AI doubt solver and a study plan for Madhya Pradesh Board Class 12 Accountancy. Free to start, no card needed.