Reconstitution of a Partnership Firm – Admission of a Partner — NCERT Solutions
Madhya Pradesh Board · Class 12 · Accountancy
NCERT Solutions for Reconstitution of a Partnership Firm – Admission of a Partner, Madhya Pradesh Board Class 12 Accountancy: 64 textbook questions solved.
Interactive on Super Tutor
Studying Reconstitution of a Partnership Firm – Admission of a Partner? Get the full interactive chapter.
Quizzes, flashcards, AI doubt-solver and a step-by-step study plan — built for NCERT solutions and more.
Free trial, no card needed.
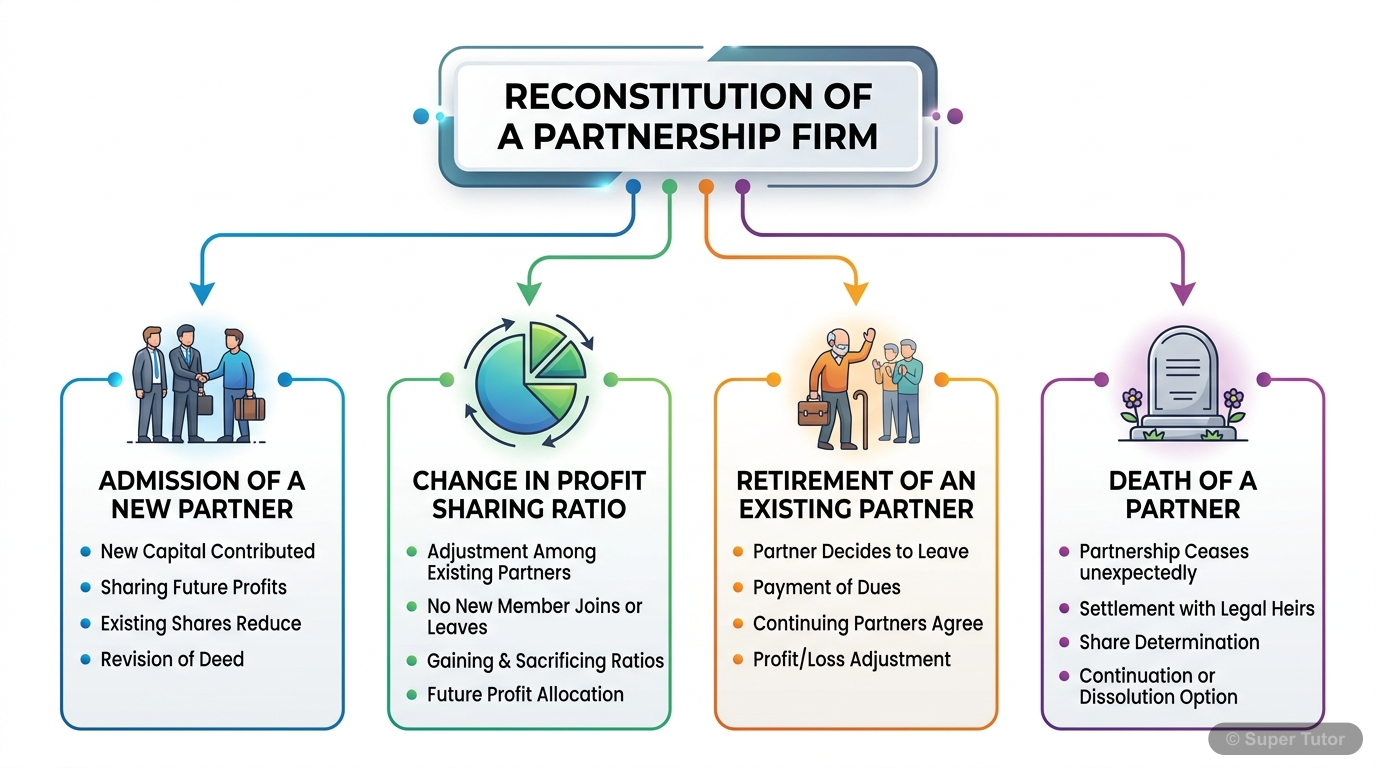
One of 15 illustrations for Reconstitution of a Partnership Firm – Admission of a Partner in Super Tutor — alongside flashcards, concept maps and practice questions.
The first 32 solutions are open to read. The other 32 are free with a Super Tutor account.
Test your Understanding - I
1A and B are partners sharing profits in the ratio of 3:1. They admit C for 1/4 share in the future profits. The new profit sharing ratio will be:
(a) A 9/16, B 3/16, C 4/16
(b) A 8/16, B 4/16, C 4/16
(c) A 10/16, B 2/16, C 4/16
(d) A 8/16, B 9/16, C 10/16Show solution
Correct Answer: (a) A , B , C
Given:
- Old ratio of A : B = 3 : 1
- C's share = 1/4
Working:
Remaining share for A and B =
A's new share =
B's new share =
C's share =
New profit sharing ratio = A : B : C = = 9 : 3 : 4
This matches option (a).
2X and Y share profits in the ratio of 3:2. Z was admitted as a partner who gets 1/5 share. New profit sharing ratio, if Z acquires 3/20 from X and 1/20 from Y would be:
(a) 9:7:4
(b) 8:8:4
(c) 6:10:4
(d) 10:6:4Show solution
Correct Answer: (a) 9 : 7 : 4
Given:
- Old ratio X : Y = 3 : 2, i.e., X = 3/5, Y = 2/5
- Z's share = 1/5 (acquired 3/20 from X and 1/20 from Y)
Working:
X's new share =
Y's new share =
Z's share =
New profit sharing ratio = X : Y : Z = = 9 : 7 : 4
3A and B share profits and losses in the ratio of 3:1. C is admitted into partnership for 1/4 share. The sacrificing ratio of A and B is:
(a) equal
(b) 3:1
(c) 2:1
(d) 3:2Show solution
Correct Answer: (b) 3 : 1
Reasoning:
When no specific agreement is mentioned about the manner in which C acquires his share, it is assumed that A and B sacrifice in their old profit sharing ratio, i.e., 3 : 1.
Verification:
C's share = 1/4. Remaining share = 3/4 distributed in ratio 3:1.
A's sacrifice =
B's sacrifice =
Sacrificing ratio = 3 : 1 (same as old ratio).
Test your Understanding - II
1At the time of admission of a new partner, general reserve appearing in the old balance sheet is transferred to:
(a) all partner's capital account
(b) new partner's capital account
(c) old partner's capital account
(d) none of the above.Show solution
Correct Answer: (c) old partner's capital account
Reasoning: General reserve represents accumulated profits earned by the firm before the admission of the new partner. The new partner has no claim over such reserves. Therefore, at the time of admission, general reserve is transferred to the old partners' capital accounts in their old profit sharing ratio.
2Asha and Nisha are partners sharing profit in the ratio of 2:1. Asha's son Ashish was admitted for 1/4 share of which 1/8 was gifted by Asha to her son. The remaining was contributed by Nisha. Goodwill of the firm is valued at Rs. 40,000. How much of the goodwill will be credited to the old partner's capital account?
(a) Rs. 2,500 each
(b) Rs. 5,000 each
(c) Rs. 20,000 each
(d) None of the above.Show solution
Correct Answer: (b) Rs. 5,000 each
Given:
- Old ratio Asha : Nisha = 2 : 1
- Ashish admitted for 1/4 share
- Asha gifted 1/8 to Ashish; Nisha contributed remaining 1/8
- Goodwill = Rs. 40,000
Working:
Ashish's share = 1/4 = 2/8
Asha's sacrifice = 1/8; Nisha's sacrifice = 1/8
Sacrificing ratio = Asha : Nisha = 1/8 : 1/8 = 1 : 1
Ashish's share of goodwill = Rs. 10,000
This Rs. 10,000 is credited to Asha and Nisha in sacrificing ratio 1:1:
- Asha's share = Rs. 5,000
- Nisha's share = Rs. 5,000
3A, B and C are partners in a firm. If D is admitted as a new partner:
(a) old firm is dissolved
(b) old firm and old partnership is dissolved
(c) old partnership is reconstituted
(d) None of the above.Show solution
Correct Answer: (c) old partnership is reconstituted
Reasoning: On admission of a new partner, the old partnership agreement comes to an end and a new partnership agreement is formed. However, the firm continues its business — it is not dissolved. Hence, the old partnership is reconstituted (not dissolved).
4On the admission of a new partner increase in the value of assets is debited to:
(a) Profit and Loss Adjustment account
(b) Assets account
(c) Old partner's capital account
(d) None of the above.Show solution
Correct Answer: (b) Assets account
Reasoning: When the value of an asset increases on revaluation, the asset account is debited (to show the increased value) and the Revaluation Account (Profit and Loss Adjustment Account) is credited. So the debit entry goes to the Assets account.
5At the time of admission of a partner, undistributed profits appearing in the balance sheet of the old firm is transferred to the capital account of:
(a) old partners in old profit sharing ratio
(b) old partners in new profit sharing ratio
(c) all the partners in the new profit sharing ratio.Show solution
Correct Answer: (a) old partners in old profit sharing ratio
Reasoning: Undistributed profits (e.g., credit balance of Profit & Loss Account) were earned by the firm before the admission of the new partner. The new partner has no right over these profits. Therefore, they are transferred to the old partners' capital accounts in their old profit sharing ratio.
Do It Yourself (Goodwill Valuation)
1A firm's profits for the last three years are Rs. 5,00,000; Rs. 4,00,000 and Rs. 6,00,000. Calculate value of firm's goodwill on the basis of four years' purchase of the average profits for the last three years.Show solution
Given:
- Profits: Rs. 5,00,000; Rs. 4,00,000; Rs. 6,00,000
- Years of purchase = 4
Step 1: Calculate Average Profits
Step 2: Calculate Goodwill
2A firm's profits during 2013, 2014, 2015 and 2016 were Rs. 16,000; Rs. 20,000; Rs. 24,000 and Rs. 32,000 respectively. The firm has capital investment of Rs. 1,00,000. A fair rate of return on investment is 18% p.a. Compute goodwill based on three years' purchase of the average super profits for the last four years.Show solution
Given:
- Profits: Rs. 16,000; Rs. 20,000; Rs. 24,000; Rs. 32,000
- Capital Investment = Rs. 1,00,000
- Normal Rate of Return = 18%
- Years of purchase = 3
Step 1: Average Profit
Step 2: Normal Profit
Step 3: Super Profit
Step 4: Goodwill
3Based on the data given in the above question, calculate goodwill by capitalisation of super profits method. Will the amount of goodwill be different if it is computed by capitalisation of average profits? Confirm your answer by numerical verification.Show solution
Using data from Q2: Average Profit = Rs. 23,000; Normal Profit = Rs. 18,000; Super Profit = Rs. 5,000; Normal Rate = 18%
Method 1: Capitalisation of Super Profits
Method 2: Capitalisation of Average Profits
Conclusion: Both methods give the same result (Rs. 27,778). The amount of goodwill is NOT different under both methods — they are equivalent approaches.
4Giri and Shanta are partners in a firm sharing profits equally. They admit Kachroo into partnership who, in addition to capital, brings Rs. 20,000 as goodwill for 1/5th share of profits in the firm. What shall be journal entries if:
(a) no goodwill appears in the books of the firm.
(b) goodwill appears in the books of the firm at Rs. 40,000.Show solution
Given:
- Old ratio Giri : Shanta = 1 : 1
- Kachroo's share = 1/5
- Goodwill brought by Kachroo = Rs. 20,000
Sacrificing Ratio (Giri : Shanta = 1 : 1, sacrifice equally)
Goodwill distributed: Giri = Rs. 10,000; Shanta = Rs. 10,000
(a) When no goodwill appears in the books:
| Journal Entry | Dr. (Rs.) | Cr. (Rs.) |
|---|---|---|
| Cash/Bank A/c Dr. | 20,000 | |
|  To Premium for Goodwill A/c | 20,000 | |
| (Goodwill brought in cash by Kachroo) |
| Dr. (Rs.) | Cr. (Rs.) | |
|---|---|---|
| Premium for Goodwill A/c Dr. | 20,000 | |
|  To Giri's Capital A/c | 10,000 | |
|  To Shanta's Capital A/c | 10,000 | |
| (Goodwill distributed in sacrificing ratio 1:1) |
(b) When goodwill appears in the books at Rs. 40,000:
First, write off existing goodwill in old ratio (1:1):
| Journal Entry | Dr. (Rs.) | Cr. (Rs.) |
|---|---|---|
| Giri's Capital A/c Dr. | 20,000 | |
| Shanta's Capital A/c Dr. | 20,000 | |
|  To Goodwill A/c | 40,000 | |
| (Existing goodwill written off in old ratio) |
Then record Kachroo's goodwill as in part (a):
| Journal Entry | Dr. (Rs.) | Cr. (Rs.) |
|---|---|---|
| Cash/Bank A/c Dr. | 20,000 | |
|  To Premium for Goodwill A/c | 20,000 |
| Dr. (Rs.) | Cr. (Rs.) | |
|---|---|---|
| Premium for Goodwill A/c Dr. | 20,000 | |
|  To Giri's Capital A/c | 10,000 | |
|  To Shanta's Capital A/c | 10,000 |
Do It Yourself (Revaluation and Admission)
1Aslam, Jackab, Hari are equal partners with capitals of Rs. 1,500, Rs. 1,750 and Rs. 2,000 respectively. They agree to admit Satnam into equal partnership upon payment in cash of Rs. 1,500 for one-fourth share of the goodwill and Rs. 1,800 as his capital, both sums to remain in the business. The liabilities of the old firm amount Rs. 3,000 and the assets, apart from cash, consist of Motors Rs. 1,200, Furniture Rs. 400, Stock Rs. 2,650, Debtors of Rs. 3,780. The Motors and Furniture were revalued at Rs. 950 and Rs. 380 respectively, and the depreciation written-off. Ascertain cash in hand and prepare the balance sheet of the firm after Satnam's admission.Show solution
Given:
- Old partners: Aslam, Jackab, Hari — equal ratio (1:1:1)
- Capitals: Aslam Rs. 1,500; Jackab Rs. 1,750; Hari Rs. 2,000
- Satnam pays Rs. 1,500 for 1/4 goodwill + Rs. 1,800 as capital
- Liabilities = Rs. 3,000
- Assets (excluding cash): Motors Rs. 1,200; Furniture Rs. 400; Stock Rs. 2,650; Debtors Rs. 3,780
- Revalued: Motors Rs. 950; Furniture Rs. 380
Step 1: Find Cash in Hand (before Satnam's admission)
Total Assets = Total Liabilities + Capital
Assets excluding cash = 1,200 + 400 + 2,650 + 3,780 = Rs. 8,030
Step 2: Revaluation Loss
- Motors: 1,200 − 950 = Rs. 250 (loss)
- Furniture: 400 − 380 = Rs. 20 (loss)
- Total Revaluation Loss = Rs. 270
Shared equally: Rs. 90 each (Aslam, Jackab, Hari)
Step 3: Adjusted Capitals (after revaluation)
- Aslam: 1,500 − 90 = Rs. 1,410
- Jackab: 1,750 − 90 = Rs. 1,660
- Hari: 2,000 − 90 = Rs. 1,910
Step 4: Goodwill Treatment
Satnam pays Rs. 1,500 for 1/4 share of goodwill → Total goodwill = Rs. 6,000
Goodwill credited to old partners equally: Rs. 500 each
- Aslam: 1,410 + 500 = Rs. 1,910
- Jackab: 1,660 + 500 = Rs. 2,160
- Hari: 1,910 + 500 = Rs. 2,410
- Satnam's Capital = Rs. 1,800
Step 5: Cash in Hand after admission
Balance Sheet of the New Firm after Satnam's Admission
| Liabilities | Rs. | Assets | Rs. |
|---|---|---|---|
| Creditors | 3,000 | Cash in Hand | 3,520 |
| Capital — Aslam | 1,910 | Debtors | 3,780 |
| Capital — Jackab | 2,160 | Stock | 2,650 |
| Capital — Hari | 2,410 | Motors | 950 |
| Capital — Satnam | 1,800 | Furniture | 380 |
| Total | 11,280 | Total | 11,280 |
2Benu and Sunil are partners sharing profits in the ratio of 3:2 on April 1, 2017. Ina was admitted for 1/4 share who paid Rs. 2,00,000 as capital and Rs. 1,00,000 for premium for goodwill in cash. At the time of admission, general reserve amounting to Rs. 1,20,000 and profit and loss account amounting to Rs. 60,000 appeared on the liability side of the balance sheet. Required: Record necessary journal entries to record the above transactions.Show solution
Given:
- Old ratio Benu : Sunil = 3 : 2
- Ina admitted for 1/4 share
- Ina brings: Capital Rs. 2,00,000 + Goodwill Rs. 1,00,000
- General Reserve = Rs. 1,20,000; P&L (Cr.) = Rs. 60,000
Sacrificing Ratio = Old ratio = 3 : 2
Goodwill distributed: Benu = = Rs. 60,000; Sunil = Rs. 40,000
Journal Entries:
1. Ina's capital and goodwill brought in:
(Being capital and goodwill premium brought in by Ina)
2. Goodwill distributed to old partners:
(Being goodwill premium credited to old partners in sacrificing ratio 3:2)
3. General Reserve transferred to old partners:
(Being general reserve distributed in old ratio 3:2)
4. Profit & Loss Account transferred to old partners:
(Being P&L credit balance distributed in old ratio 3:2)
3Ashoo and Rahul are partners sharing profits in the ratio of 5:3. Gaurav was admitted for 1/5 share and was asked to contribute proportionate capital and Rs. 4,000 for premium (goodwill). The Capitals of Ashoo and Rahul, after all adjustments relating to revaluation, goodwill etc., worked out to be Rs. 45,000 and Rs. 35,000 respectively. Required: Calculate New Profit sharing ratio, capital to be brought in by Gaurav and record necessary journal entries for the same.Show solution
Given:
- Old ratio Ashoo : Rahul = 5 : 3
- Gaurav's share = 1/5
- Goodwill brought by Gaurav = Rs. 4,000
- Adjusted capitals: Ashoo = Rs. 45,000; Rahul = Rs. 35,000
Step 1: New Profit Sharing Ratio
Remaining share =
Ashoo's new share =
Rahul's new share =
Gaurav's share =
Converting to common denominator (40):
- Ashoo = 20/40; Rahul = 12/40; Gaurav = 8/40
New ratio = 20 : 12 : 8 = 5 : 3 : 2
Step 2: Capital to be brought in by Gaurav
Total capital of new firm (based on old partners' adjusted capitals):
Old partners hold 4/5 of total capital = 45,000 + 35,000 = Rs. 80,000
Gaurav's capital =
Step 3: Sacrificing Ratio = Old ratio = 5 : 3
Goodwill: Ashoo = = Rs. 2,500; Rahul = = Rs. 1,500
Journal Entries:
1. Gaurav brings capital and goodwill:
2. Goodwill distributed to old partners:
Short Answer Questions
1Identify various matters that need adjustments at the time of admission of a new partner.Show solution
At the time of admission of a new partner, the following matters require adjustments:
- New Profit Sharing Ratio and Sacrificing Ratio: The new profit sharing ratio of all partners (old and new) must be determined. The sacrificing ratio of old partners must also be calculated.
- Goodwill: The goodwill of the firm must be valued and the new partner must compensate the old partners for their sacrifice. Adjustments are made through the new partner's capital account or cash brought in.
- Revaluation of Assets and Liabilities: Assets and liabilities are revalued to reflect their current fair values. Any gain or loss on revaluation is shared among old partners in their old profit sharing ratio.
- Accumulated Profits and Losses (Reserves): Any undistributed profits, general reserves, or accumulated losses appearing in the balance sheet are transferred to old partners' capital accounts in their old profit sharing ratio.
- Adjustment of Partners' Capitals: If agreed, the capitals of all partners are adjusted to be proportionate to their new profit sharing ratio.
2Why it is necessary to ascertain new profit sharing ratio even for old partners when a new partner is admitted?Show solution
When a new partner is admitted, he acquires a share in the profits of the firm. This share is contributed (sacrificed) by the old partners. As a result, the old partners' shares in profits change (reduce).
It is necessary to ascertain the new profit sharing ratio for old partners because:
- Future profit distribution must be done in the correct new ratio.
- Goodwill adjustment — the sacrificing ratio (derived from old and new shares) determines how much goodwill credit each old partner receives.
- Capital adjustments — if capitals are to be proportionate to profit sharing ratio, the new ratio is needed.
- Correct accounting — all future transactions, drawings, and settlements depend on the new ratio.
Without determining the new ratio, it would be impossible to distribute profits correctly among all partners.
3What is sacrificing ratio? Why is it calculated?Show solution
Sacrificing Ratio:
Sacrificing ratio is the ratio in which the old partners agree to give up (sacrifice) a part of their share in profits in favour of the new partner. It is calculated as:
Why it is calculated:
- Goodwill distribution: The premium for goodwill brought in by the new partner is distributed among the old partners in their sacrificing ratio. Each old partner is compensated in proportion to the share they have sacrificed.
- Fairness: It ensures that each old partner is compensated fairly for the share of profit they have given up to the new partner.
- Hidden goodwill adjustment: Even when goodwill is not brought in cash, the adjustment entry for goodwill is made using the sacrificing ratio.
Usually, the sacrificing ratio is the same as the old profit sharing ratio, but it can differ based on the agreement between partners.
4On what occasions sacrificing ratio is used?Show solution
Sacrificing ratio is used on the following occasions:
- At the time of admission of a new partner: The premium for goodwill brought in by the new partner is credited to the old partners' capital accounts in their sacrificing ratio.
- When the new partner cannot bring goodwill in cash: The new partner's capital account is debited and the old partners' capital accounts are credited in the sacrificing ratio.
- When goodwill already exists in the books: After writing off existing goodwill, the new goodwill premium is distributed in the sacrificing ratio.
- When there is a change in profit sharing ratio among existing partners: The partner who gains in profit share compensates the partner who sacrifices, and the sacrificing ratio determines the amount of compensation.
5If some goodwill already exists in the books and the new partner brings in his share of goodwill in cash, how will you deal with existing amount of goodwill?Show solution
Treatment of Existing Goodwill when New Partner Brings Goodwill in Cash:
When goodwill already appears in the books of the firm and the new partner brings his share of goodwill in cash, the following procedure is followed:
Step 1: Write off the existing goodwill by debiting the old partners' capital accounts in their old profit sharing ratio:
Step 2: Record the goodwill brought in by the new partner:
Step 3: Distribute the premium for goodwill among old partners in their sacrificing ratio:
This ensures that the goodwill account does not appear in the new firm's balance sheet (as per AS-26), and old partners are compensated for their sacrifice.
6Why there is need for the revaluation of assets and liabilities on the admission of a partner?Show solution
Need for Revaluation of Assets and Liabilities on Admission of a Partner:
At the time of admission of a new partner, assets and liabilities are revalued for the following reasons:
- Fair representation: The book values of assets and liabilities may not reflect their current market values. Revaluation ensures that the balance sheet shows true and fair values.
- Equity among partners: Any increase or decrease in the value of assets and liabilities that occurred during the period when only the old partners were in the firm should benefit or be borne by the old partners only. The new partner should neither gain nor lose on account of changes that occurred before his admission.
- Correct capital accounts: The old partners' capital accounts are adjusted for the gain or loss on revaluation before the new partner joins, ensuring that the new partner starts with a fair position.
- Unrecorded assets/liabilities: Sometimes certain assets or liabilities may be unrecorded. Revaluation helps bring them into the books.
The gain or loss on revaluation is transferred to old partners' capital accounts in their old profit sharing ratio.
Long Answer Questions
1Do you advise that assets and liabilities must be revalued at the time of admission of a partner? If so, why? Also describe how is this treated in the book of account?Show solution
Yes, it is advisable to revalue assets and liabilities at the time of admission of a partner.
Reasons:
- True and fair view: Book values may differ from current market values due to price changes, depreciation, or appreciation. Revaluation ensures the balance sheet reflects true values.
- Protection of old partners' interests: Any appreciation or depreciation in asset values that occurred before the new partner's admission belongs to the old partners. If not revalued, the new partner would share in gains/losses that are not his.
- Correct profit/loss sharing: Without revaluation, future profits/losses would be distorted because unrealised gains or losses would be mixed with post-admission profits.
- Unrecorded items: Revaluation helps identify and record previously unrecorded assets or liabilities.
Accounting Treatment — Revaluation Account (Profit & Loss Adjustment Account):
| Revaluation Account | |
|---|---|
| Dr. side: Decrease in asset values; Increase in liability values; Unrecorded liabilities | Cr. side: Increase in asset values; Decrease in liability values; Unrecorded assets |
- If Credit side > Debit side → Gain on Revaluation → Credited to old partners' capital accounts in old ratio.
- If Debit side > Credit side → Loss on Revaluation → Debited to old partners' capital accounts in old ratio.
Journal Entries:
For increase in asset value:
For decrease in asset value:
For gain on revaluation:
For loss on revaluation:
2What is goodwill? What factors affect goodwill?Show solution
Meaning of Goodwill:
Goodwill is the value of the reputation, good name, and business connections of a firm that enables it to earn profits in excess of the normal rate of return. It is an intangible asset that arises from the favourable impression a business has created in the minds of its customers, suppliers, and the public over a period of time.
In accounting terms: Goodwill = Capitalised Value of Firm − Net Assets (Capital Employed)
Or: Goodwill = Super Profit × Years of Purchase
Factors Affecting Goodwill:
- Nature of business: Firms with stable and regular demand (e.g., essential goods) have higher goodwill.
- Location: A business situated at a prime or convenient location enjoys higher goodwill.
- Quality of products/services: Superior quality products and after-sales service enhance goodwill.
- Management efficiency: Competent and experienced management leads to higher profits and goodwill.
- Favourable contracts: Long-term contracts with suppliers or customers add to goodwill.
- Capital required: Businesses requiring less capital to earn the same profit have higher goodwill.
- Trend of profits: A consistent upward trend in profits increases goodwill.
- Reputation and brand name: A well-known brand or trademark enhances goodwill significantly.
- Market position: Monopoly or dominant market position increases goodwill.
- Risk involved: Lower risk businesses command higher goodwill.
3Explain various methods of valuation of goodwill.Show solution
Methods of Valuation of Goodwill:
1. Average Profits Method:
Goodwill is calculated as a certain number of years' purchase of the average profits.
Example: If average profit = Rs. 50,000 and years of purchase = 3, then Goodwill = Rs. 1,50,000.
2. Super Profits Method:
Super profit is the excess of actual/average profit over normal profit.
3. Capitalisation Method:
This has two sub-methods:
(a) Capitalisation of Average Profits:
(b) Capitalisation of Super Profits:
Both sub-methods give the same result.
Note: The choice of method depends on the agreement between the partners. Each method may give a different value of goodwill.
4If it is agreed that the capital of all the partners should be proportionate to the new profit sharing ratio, how will you work out the new capital of each partner? Give examples and state how necessary adjustments will be made.Show solution
Adjustment of Capitals in Proportion to New Profit Sharing Ratio:
When partners agree that their capitals should be proportionate to the new profit sharing ratio, the following steps are followed:
Step 1: Determine the new profit sharing ratio.
Step 2: Use the new partner's capital as the base (or total capital as given) to calculate the required capital of each partner.
OR if total capital is given:
Step 3: Compare required capital with actual capital (after all adjustments for goodwill, revaluation, reserves).
- If Required > Actual → Partner brings in the shortfall (debit Bank, credit Capital)
- If Required < Actual → Partner withdraws the excess (debit Capital, credit Bank or Current A/c)
Example:
A and B share profits 2:1. C is admitted for 1/4 share. New ratio = 2:1:1. C brings Rs. 20,000 as capital. Adjusted capitals: A = Rs. 45,000; B = Rs. 15,000.
Total capital based on C = Rs. 80,000
Required: A = Rs. 40,000; B = Rs. 20,000
- A has Rs. 45,000 but needs Rs. 40,000 → Withdraw Rs. 5,000
- B has Rs. 15,000 but needs Rs. 20,000 → Bring in Rs. 5,000
Journal Entries:
5Explain how will you deal with goodwill when new partner is not in a position to bring his share of goodwill in cash.Show solution
Treatment of Goodwill when New Partner Cannot Bring it in Cash:
When the new partner is unable to bring his share of goodwill premium in cash, the adjustment is made through capital accounts without any cash transaction. Two methods are used:
Method 1: Through Goodwill Account (Raising and Writing Off)
Step 1: Raise goodwill in the books by crediting old partners in old ratio:
Step 2: Write off goodwill by debiting all partners (including new) in new ratio:
The net effect is that the new partner's capital account is debited for his share of goodwill and old partners are credited in their sacrificing ratio.
Method 2: Direct Adjustment (Without Opening Goodwill Account)
The new partner's capital account is directly debited and old partners' capital accounts are credited in their sacrificing ratio:
This method is simpler and does not create a goodwill account in the books, which is in line with AS-26 (goodwill should not be shown as an asset unless purchased).
Both methods produce the same net effect on the capital accounts of all partners.
6Explain various methods for the treatment of goodwill on the admission of a new partner.Show solution
Methods for Treatment of Goodwill on Admission of a New Partner:
Case 1: New Partner Brings Goodwill in Cash (Premium Method)
If old partners withdraw the amount: Debit their capital accounts and credit Bank.
Case 2: New Partner Brings Part of Goodwill in Cash
Record cash received, credit old partners for full goodwill in sacrificing ratio, and debit new partner's capital for the balance not brought in cash.
Case 3: New Partner Cannot Bring Goodwill in Cash
Method A — Raising and Writing Off Goodwill:
- Raise goodwill: Credit old partners in old ratio
- Write off goodwill: Debit all partners in new ratio
Method B — Direct Adjustment:
Case 4: Goodwill Already Exists in Books
- First write off existing goodwill by debiting old partners in old ratio
- Then treat new goodwill as per Cases 1, 2, or 3 above
Case 5: Hidden Goodwill
When goodwill is not given, it is inferred:
7How will you deal with the accumulated profits and losses and reserves on the admission of a new partner?Show solution
Treatment of Accumulated Profits, Losses and Reserves on Admission:
At the time of admission of a new partner, any accumulated profits, reserves, or losses appearing in the balance sheet must be dealt with as follows:
1. Accumulated Profits / General Reserve / Reserve Fund (Credit Balance):
These belong to the old partners as they were earned before the new partner's admission. They are transferred to old partners' capital accounts in their old profit sharing ratio:
2. Accumulated Losses (Debit Balance of P&L Account) / Deferred Revenue Expenditure:
These are losses incurred before the new partner's admission and must be borne by old partners only:
Reason: The new partner should neither benefit from past profits nor bear past losses. All such items must be cleared before the new partner joins, ensuring a clean start for the reconstituted firm.
Note: The new profit sharing ratio is NOT used for this adjustment — only the old profit sharing ratio is used.
8At what figures the value of assets and liabilities appear in the books of the firm after revaluation has been done. Show with the help of an imaginary balance sheet.Show solution
Values of Assets and Liabilities After Revaluation:
After revaluation, assets and liabilities appear at their revised (revalued) figures in the new balance sheet. The old book values are replaced by the new revalued amounts.
Example:
Suppose A and B are partners (old ratio 2:1). C is admitted. The following revaluations are made:
- Land & Building: increased from Rs. 50,000 to Rs. 60,000
- Stock: decreased from Rs. 20,000 to Rs. 18,000
- Provision for Doubtful Debts: created at Rs. 1,000 on Debtors of Rs. 20,000
Revaluation Account:
| Dr. | Rs. | Cr. | Rs. |
|---|---|---|---|
| Stock A/c | 2,000 | Land & Building A/c | 10,000 |
| Provision for D.D. | 1,000 | ||
| Gain (A: 4,667; B: 2,333) | 7,000 | ||
| Total | 10,000 | Total | 10,000 |
Balance Sheet (Extract) After Revaluation:
| Assets | Rs. |
|---|---|
| Land & Building | 60,000 (revalued up) |
| Stock | 18,000 (revalued down) |
| Debtors | 20,000 |
| Less: Provision for D.D. | (1,000) |
| Net Debtors | 19,000 |
Conclusion: After revaluation, assets appear at their new revalued figures (not original book values), and liabilities are adjusted to reflect their current obligations. The gain/loss on revaluation is distributed among old partners before the new partner joins.
Numerical Questions
1A and B were partners in a firm sharing profits and losses in the ratio of 3:2. They admit C into the partnership with 1/6 share in the profits. Calculate the new profit sharing ratio.Show solution
Given:
- Old ratio A : B = 3 : 2
- C's share = 1/6
Working:
Remaining share for A and B =
A's new share =
B's new share =
C's share =
New ratio = = 3 : 2 : 1
2A, B, C were partners in a firm sharing profits in 3:2:1 ratio. They admitted D for 10% profits. Calculate the new profit sharing ratio.Show solution
Given:
- Old ratio A : B : C = 3 : 2 : 1
- D's share = 10% = 1/10
Working:
Remaining share =
A's new share =
B's new share =
C's new share =
D's share =
New ratio = = 9 : 6 : 3 : 2
3X and Y are partners sharing profits in 5:3 ratio admitted Z for 1/10 share which he acquired equally from X and Y. Calculate new profit sharing ratio.Show solution
Given:
- Old ratio X : Y = 5 : 3
- Z's share = 1/10, acquired equally from X and Y
- X's sacrifice = Y's sacrifice =
Working:
X's new share =
Y's new share =
Z's share =
New ratio = X : Y : Z = 23 : 13 : 4
Free with a Super Tutor account
Free with a Super Tutor account
Free with a Super Tutor account
Free with a Super Tutor account
Free with a Super Tutor account
Free with a Super Tutor account
Free with a Super Tutor account
Free with a Super Tutor account
Free with a Super Tutor account
Free with a Super Tutor account
Free with a Super Tutor account
Free with a Super Tutor account
Free with a Super Tutor account
Free with a Super Tutor account
a) When the amount of goodwill is retained in the business.
b) When the amount of goodwill is fully withdrawn.
c) When 50% of the amount of goodwill is withdrawn.
d) When goodwill is paid privately.
Free with a Super Tutor account
Free with a Super Tutor account
Free with a Super Tutor account
Free with a Super Tutor account
Free with a Super Tutor account
Free with a Super Tutor account
a) Goodwill already appears in the books at Rs. 2,02,500.
b) Goodwill appears in the books at Rs. 2,500.
c) Goodwill appears in the books at Rs. 2,05,000.
Free with a Super Tutor account
Free with a Super Tutor account
Free with a Super Tutor account
Free with a Super Tutor account
Free with a Super Tutor account
Free with a Super Tutor account
Free with a Super Tutor account
Free with a Super Tutor account
Free with a Super Tutor account
Free with a Super Tutor account
Free with a Super Tutor account
Free with a Super Tutor account
32 more solved questions in Reconstitution of a Partnership Firm – Admission of a Partner
They are free with a Super Tutor account, along with practice quizzes and flashcards for this chapter. Free to start, no card needed.
Frequently Asked Questions
What are the important topics in Reconstitution of a Partnership Firm – Admission of a Partner for Madhya Pradesh Board Class 12 Accountancy?
Are these NCERT Solutions for Reconstitution of a Partnership Firm – Admission of a Partner free?
How should I revise Reconstitution of a Partnership Firm – Admission of a Partner for the Madhya Pradesh Board Class 12 board exam?
Sources & Official References
Content is aligned to the official syllabus. Refer to the board website for the latest curriculum.
More resources for Reconstitution of a Partnership Firm – Admission of a Partner
Practice Quiz
Test yourself with a quick quiz
Important Questions
Exam-style questions with answers
Revision Notes
Key points for last-minute revision
Formula Sheet
The chapter's formulas in one place
Chapter Summary
Understand the chapter at a glance
Concept Maps
See how topics connect
Study Plan
Step-by-step plan for this chapter
Flashcards
Quick-fire cards for active recall
Syllabus
What topics to cover
For serious students
Get the full Reconstitution of a Partnership Firm – Admission of a Partner chapter — start free.
Quizzes, flashcards, an AI doubt solver and a study plan for Madhya Pradesh Board Class 12 Accountancy. Free to start, no card needed.