Reconstitution of a Partnership Firm – Admission of a Partner — NCERT Solutions
CBSE · Class 12 · Accountancy
NCERT question answers for Reconstitution of a Partnership Firm – Admission of a Partner, CBSE Class 12 Accountancy: 8 textbook questions solved step by.
Interactive on Super Tutor
Studying Reconstitution of a Partnership Firm – Admission of a Partner? Get the full interactive chapter.
Quizzes, flashcards, AI doubt-solver and a step-by-step study plan — built for NCERT solutions and more.
Free trial, no card needed.
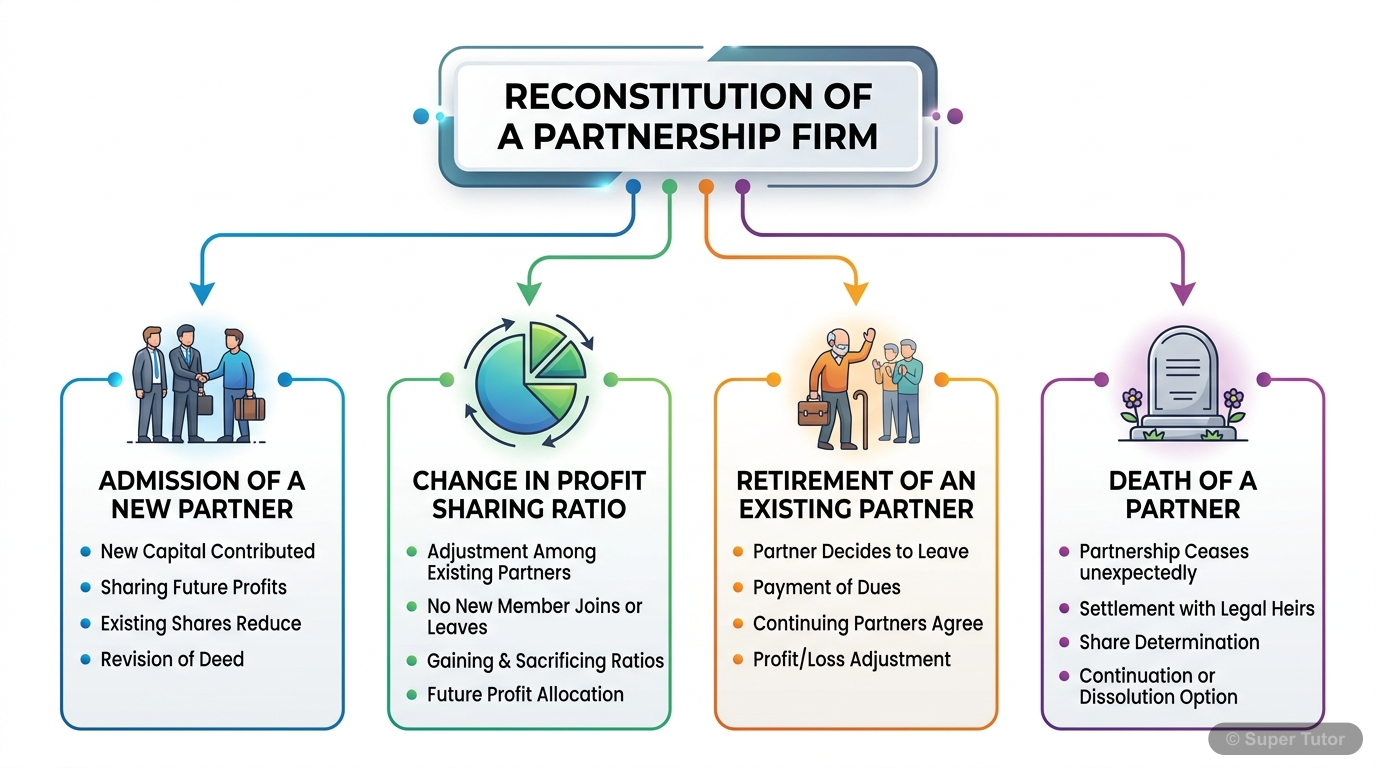
One of 15 illustrations for Reconstitution of a Partnership Firm – Admission of a Partner in Super Tutor — alongside flashcards, concept maps and practice questions.
See them allThe first 4 solutions are open to read. The other 4 are free with a Super Tutor account. Unlock all 8 free in Super Tutor
Test your Understanding - I
1A and B are partners sharing profits in the ratio of 3:1. They admit C for 1/4 share in the future profits. The new profit sharing ratio will be:- (a) A , B , C
- (b) A , B , C
- (c) A , B , C
- (d) A , B , C
Show solution
- (a) A , B , C
- (b) A , B , C
- (c) A , B , C
- (d) A , B , C
C’s share = .
Remaining share for A and B = .
Old ratio of A:B = 3:1, so they share the remaining in the ratio 3:1.
- A’s share =
- B’s share =
- C’s share =
So the new ratio is . The printed options do not show this exact ratio; the book’s illustration, however, gives the method. Among the given options, none matches the correct ratio exactly.
Not sure why a step works? check your working in Super Tutor
2X and Y share profits in the ratio of 3:2. Z was admitted as a partner who sets 1/5 share. New profit sharing ratio, if Z acquires 3/20 from X and 1/20 from Y would be:- (a) 9 : 7 : 4 (b) 8 : 8 : 4 (c) 6 : 10 : 4 (d) 10 : 6 : 4
Show solution
- (a) 9 : 7 : 4 (b) 8 : 8 : 4 (c) 6 : 10 : 4 (d) 10 : 6 : 4
X and Y share profits in the ratio 3:2, so their old shares are:
- X =
- Y =
Z gets , and acquires:
- from X
- from Y
So new shares are:
- X =
- Y =
- Z =
New profit sharing ratio = 9 : 7 : 4.
Not sure why a step works? check your working in Super Tutor
3A and B share profits and losses in the ratio of 3 : 1, C is admitted into partnership for 1/4 share. The sacrificing ratio of A and B is:- (a) equal (b) 3 : 1 (c) 2 : 1 (d) 3 : 2.
Show solution
- (a) equal (b) 3 : 1 (c) 2 : 1 (d) 3 : 2.
A and B share profits in the ratio 3:1.
Since nothing else is stated, the new partner is assumed to acquire his share from the old partners in their old ratio. Therefore, their sacrificing ratio is the same as the old ratio:
A : B = 3 : 1.
Not sure why a step works? check your working in Super Tutor
Test your Understanding – II
1At the time of admission of a new partner, general reserve appearing in the old balance sheet is transferred to:Choose the correct alternative –
- (a) all partner's capital account
- (b) new partner's capital account
- (c) old partner's capital account
- (d) none of the above.
Show solution
Choose the correct alternative –
- (a) all partner's capital account
- (b) new partner's capital account
- (c) old partner's capital account
- (d) none of the above.
At the time of admission, any general reserve already appearing in the old balance sheet is an undistributed accumulated profit. The new partner is not entitled to this profit, so it is transferred to the old partners' capital accounts in the old profit sharing ratio. Therefore, the correct option is (c).
Not sure why a step works? check your working in Super Tutor
- (a) Rs. 2,500 each
- (b) Rs. 5,000 each
- (c) Rs. 20,000 each
- (d) None of the above.
Free with a Super Tutor account
Choose the correct alternative –
- (a) old firm is dissolved
- (b) old firm and old partnership is dissolved
- (c) old partnership is reconstituted
- (d) None of the above.
Free with a Super Tutor account
Choose the correct alternative –
- (a) Profit and Loss Adjustment account
- (b) Assets account
- (c) Old partner's capital account
- (d) None of the above.
Free with a Super Tutor account
Choose the correct alternative –
- (a) old partners in old profit sharing ratio
- (b) old partners in new profit sharing ratio
- (c) all the partner in the new profit sharing ratio.
Free with a Super Tutor account
4 more solved questions in Reconstitution of a Partnership Firm – Admission of a Partner
They are free with a Super Tutor account, along with practice quizzes and flashcards for this chapter. Free to start, no card needed.
Frequently Asked Questions
What are the important topics in Reconstitution of a Partnership Firm – Admission of a Partner for CBSE Class 12 Accountancy?
Are these NCERT Solutions for Reconstitution of a Partnership Firm – Admission of a Partner free?
How should I revise Reconstitution of a Partnership Firm – Admission of a Partner for the CBSE Class 12 board exam?
Sources & Official References
- NCERT Official — ncert.nic.in
- CBSE Academic — cbseacademic.nic.in
- CBSE Official — cbse.gov.in
- National Education Policy 2020 — education.gov.in
Content is aligned to the official syllabus. Refer to the board website for the latest curriculum.
More resources for Reconstitution of a Partnership Firm – Admission of a Partner
Practice Quiz
Test yourself with a quick quiz
Important Questions
Exam-style questions with answers
Revision Notes
Key points for last-minute revision
Formula Sheet
The chapter's formulas in one place
Chapter Summary
Understand the chapter at a glance
Concept Maps
See how topics connect
Study Plan
Step-by-step plan for this chapter
Flashcards
Quick-fire cards for active recall
Syllabus
What topics to cover
For serious students
Get the full Reconstitution of a Partnership Firm – Admission of a Partner chapter — start free.
Quizzes, flashcards, an AI doubt solver and a study plan for CBSE Class 12 Accountancy. Free to start, no card needed.