Accounting Ratios — NCERT Solutions
CBSE · Class 12 · Accountancy
NCERT question answers for Accounting Ratios, CBSE Class 12 Accountancy: 52 textbook questions solved step by step.
Interactive on Super Tutor
Studying Accounting Ratios? Get the full interactive chapter.
Quizzes, flashcards, AI doubt-solver and a step-by-step study plan — built for NCERT solutions and more.
Free trial, no card needed.
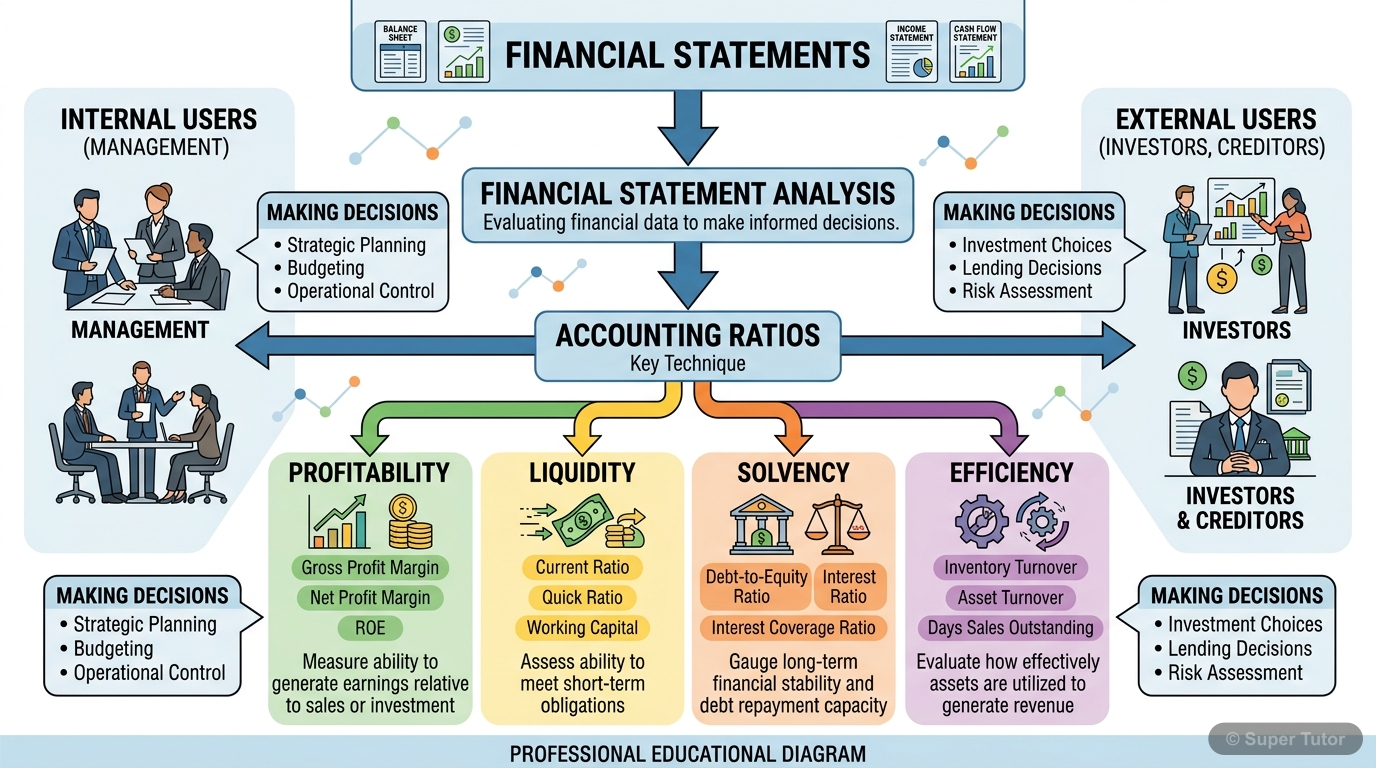
One of 15 illustrations for Accounting Ratios in Super Tutor — alongside flashcards, concept maps and practice questions.
See them allThe first 26 solutions are open to read. The other 26 are free with a Super Tutor account. Unlock all 52 free in Super Tutor
Test your Understanding – I
1(a)The only purpose of financial reporting is to keep the managers informed about the progress of operations.Show solution
The chapter says financial reporting is meant to provide financial information to meet the information needs of decision-makers. It is not only for managers.
Not sure why a step works? check your working in Super Tutor
1(b)Analysis of data provided in the financial statements is termed as financial analysis.Show solution
The chapter states that the analysis of data provided in financial statements is termed financial statement analysis. So the statement is correct in meaning.
Not sure why a step works? check your working in Super Tutor
1(c)Long-term borrowings are concerned about the ability of a firm to discharge its obligations to pay interest and repay the principal amount.Show solution
The chapter explains that solvency ratios are concerned with a firm's ability to meet long-term obligations, including paying interest and repaying the principal amount. So the statement is true.
Not sure why a step works? check your working in Super Tutor
1(d)A ratio is always expressed as a quotient of one number divided by another.Show solution
A ratio can be expressed as a fraction, proportion, percentage, or a number of times. So it is not always a quotient only.
Not sure why a step works? check your working in Super Tutor
1(e)Ratios help in comparisons of a firm's results over a number of accounting periods as well as with other business enterprises.Show solution
The chapter says ratios help in comparative analysis over many accounting periods and also with other business enterprises. Therefore the statement is true.
Not sure why a step works? check your working in Super Tutor
1(f)A ratio reflects quantitative and qualitative aspects of results.Show solution
Ratios reflect mainly quantitative or monetary aspects and ignore qualitative or non-monetary aspects. So the statement is false.
Not sure why a step works? check your working in Super Tutor
Test your Understanding – II
(i)The following groups of ratios are primarily measure risk:- A. liquidity, activity, and profitability
- B. liquidity, activity, and inventory
- C. liquidity, activity, and debt
- D. liquidity, debt and profitability
Show solution
- A. liquidity, activity, and profitability
- B. liquidity, activity, and inventory
- C. liquidity, activity, and debt
- D. liquidity, debt and profitability
The chapter states that the functional classification includes liquidity, solvency, activity, and profitability ratios. These groups are primarily measures of risk, return, and operating efficiency. Among the options, liquidity, debt and profitability is the correct match given the printed choices for risk-related groups.
Not sure why a step works? check your working in Super Tutor
(ii)The _______ ratios are primarily measures of return:- A. liquidity
- B. activity
- C. debt
- D. profitability
Show solution
- A. liquidity
- B. activity
- C. debt
- D. profitability
The chapter says profitability ratios are related to analysis of profits and are measures of return. So the correct option is profitability.
Not sure why a step works? check your working in Super Tutor
(iii)The _______ of business firm is measured by its ability to satisfy its short-term obligations as they become due:- A. activity
- B. liquidity
- C. debt
- D. profitability
Show solution
- A. activity
- B. liquidity
- C. debt
- D. profitability
The ability of a firm to satisfy its short-term obligations as they become due is called liquidity. So the correct option is B.
Not sure why a step works? check your working in Super Tutor
(iv)_______ ratios are a measure of the speed with which various accounts are converted into revenue from operations or cash:- A. activity
- B. liquidity
- C. debt
- D. profitability
Show solution
- A. activity
- B. liquidity
- C. debt
- D. profitability
Ratios that measure the speed with which accounts are converted into revenue from operations or cash are activity ratios. So the correct option is A.
Not sure why a step works? check your working in Super Tutor
(v)The two basic measures of liquidity are:A. inventory turnover and current ratio
B. current ratio and liquid ratio
C. gross profit margin and operating ratio
D. current ratio and average collection period
- A. inventory turnover and current ratio
- B. current ratio and liquid ratio
- C. gross profit margin and operating ratio
- D. current ratio and average collection period
Show solution
A. inventory turnover and current ratio
B. current ratio and liquid ratio
C. gross profit margin and operating ratio
D. current ratio and average collection period
- A. inventory turnover and current ratio
- B. current ratio and liquid ratio
- C. gross profit margin and operating ratio
- D. current ratio and average collection period
The chapter states that the two basic measures of liquidity are current ratio and liquid ratio (also called quick ratio). So the correct option is B.
Not sure why a step works? check your working in Super Tutor
(vi)The _______ is a measure of liquidity which excludes _______, generally the least liquid asset:- A. current ratio, trade receivable
- B. liquid ratio, trade receivable
- C. current ratio, inventory
- D. liquid ratio, inventory
Show solution
- A. current ratio, trade receivable
- B. liquid ratio, trade receivable
- C. current ratio, inventory
- D. liquid ratio, inventory
The liquid ratio is the liquidity measure that excludes inventory, because inventory is generally the least liquid current asset. So the correct option is D.
Not sure why a step works? check your working in Super Tutor
Test your Understanding – III
(i)The _______ is useful in evaluating credit and collection policies.- A. average payment period
- B. current ratio
- C. average collection period
- D. current asset turnover
Show solution
- A. average payment period
- B. current ratio
- C. average collection period
- D. current asset turnover
The chapter says average collection period helps in judging the speed of collection from trade receivables and is useful in evaluating credit and collection policies. So option C is correct.
Not sure why a step works? check your working in Super Tutor
(ii)The _______ measures the activity of a firm's inventory.- A. average collection period
- B. inventory turnover
- C. liquid ratio
- D. current ratio
Show solution
- A. average collection period
- B. inventory turnover
- C. liquid ratio
- D. current ratio
The ratio that measures the activity of a firm's inventory is inventory turnover ratio. So option B is correct.
Not sure why a step works? check your working in Super Tutor
(iii)The _______ may indicate that the firm is experiencing stockouts and lost sales.- A. average payment period
- B. inventory turnover ratio
- C. average collection period
- D. quick ratio
Show solution
- A. average payment period
- B. inventory turnover ratio
- C. average collection period
- D. quick ratio
A very high inventory turnover ratio may indicate stockouts and lost sales because inventory is being sold too quickly. So option B is correct.
Not sure why a step works? check your working in Super Tutor
(iv)ABC Co. extends credit terms of 45 days to its customers. Its credit collection would be considered poor if its average collection period was.A. 30 days
B. 36 days
C. 47 days
D. 37 days
- A. 30 days
- B. 36 days
- C. 47 days
- D. 37 days
Show solution
A. 30 days
B. 36 days
C. 47 days
D. 37 days
- A. 30 days
- B. 36 days
- C. 47 days
- D. 37 days
The chapter says that if a firm's customers are given 45 days credit, then credit collection would be considered poor if the average collection period is more than 45 days. Among the options, 47 days is the poor collection period.
So the correct option is C.
Not sure why a step works? check your working in Super Tutor
(v)_______ are especially interested in the average payment period, since it provides them with a sense of the bill-paying patterns of the firm.- A. Customers
- B. Stockholders
- C. Lenders and suppliers
- D. Borrowers and buyers
Show solution
- A. Customers
- B. Stockholders
- C. Lenders and suppliers
- D. Borrowers and buyers
The chapter says lenders and suppliers are especially interested in the average payment period because it shows the bill-paying pattern of the firm. So option C is correct.
Not sure why a step works? check your working in Super Tutor
(vi)The _______ ratios provide the information critical to the long run operation of the firm- A. liquidity
- B. activity
- C. solvency
- D. profitability
Show solution
- A. liquidity
- B. activity
- C. solvency
- D. profitability
The ratios that provide information critical to the long-run operation of the firm are solvency ratios. So option C is correct.
Not sure why a step works? check your working in Super Tutor
Questions for Practice
1What do you mean by Ratio Analysis?Show solution
Ratio Analysis is a technique of financial statement analysis in which financial data are regrouped and compared by using arithmetical relationships. It helps in understanding the relationship between two accounting numbers and in assessing the firm's liquidity, solvency, efficiency, and profitability.
Not sure why a step works? check your working in Super Tutor
2What are various types of ratios?Show solution
The chapter gives two classifications of ratios:
- Traditional classification
- Statement of Profit and Loss ratios
- Balance Sheet ratios
- Composite ratios
- Functional classification
- Liquidity ratios
- Solvency ratios
- Activity (or turnover) ratios
- Profitability ratios
Not sure why a step works? check your working in Super Tutor
3aInventory turnoverShow solution
The relationship studied for inventory turnover is Cost of Revenue from Operations / Average Inventory. The ratio is called the Inventory Turnover Ratio.
Not sure why a step works? check your working in Super Tutor
3bTrade receivables turnoverShow solution
The relationship studied for trade receivables turnover is Net Credit Revenue from Operations / Average Trade Receivables. The ratio is called the Trade Receivables Turnover Ratio.
Not sure why a step works? check your working in Super Tutor
3cTrade payables turnoverShow solution
The relationship studied for trade payables turnover is Net Credit Purchases / Average Trade Payables. The ratio is called the Trade Payables Turnover Ratio.
Not sure why a step works? check your working in Super Tutor
3dWorking capital turnoverShow solution
The relationship studied for working capital turnover is Net Revenue from Operations / Working Capital. The ratio is called the Working Capital Turnover Ratio.
Not sure why a step works? check your working in Super Tutor
4The liquidity of a business firm is measured by its ability to satisfy its long-term obligations as they become due. What are the ratios used for this purpose?Show solution
For studying the solvency position of a firm, the chapter says the following ratios are used:
- Debt-Equity Ratio
- Debt to Capital Employed Ratio
- Proprietary Ratio
- Total Assets to Debt Ratio
- Interest Coverage Ratio
These ratios show the firm's ability to meet its long-term obligations.
Not sure why a step works? check your working in Super Tutor
5The average age of inventory is viewed as the average length of time inventory is held by the firm for which explain with reasons.Show solution
The average age of inventory means the average length of time inventory is held before it is sold. It is related to the inventory turnover ratio and helps judge how fast stock moves. A shorter average age means inventory is sold quickly, while a longer age may indicate slow-moving or old stock.
Not sure why a step works? check your working in Super Tutor
Free with a Super Tutor account
Free with a Super Tutor account
Free with a Super Tutor account
Free with a Super Tutor account
Free with a Super Tutor account
| Particulars | Amount(Rs.) |
|---|---|
| I. Equity and Liabilities | |
| 1. Shareholders' funds | |
| a) Share capital | 24,00,000 |
| b) Reserves and surplus | 6,00,000 |
| 2. Non-current liabilities | |
| Long-term borrowings | 9,00,000 |
| 3. Current liabilities | |
| a) Short-term borrowings | 6,00,000 |
| b) Trade payables | 23,40,000 |
| c) Short-term provisions | 60,000 |
| Total | 69,00,000 |
| II. Assets | |
| 1. Non-current assets | |
| Fixed assets | |
| - Tangible assets | 45,00,000 |
| 2. Current Assets | |
| a) Inventories | 12,00,000 |
| b) Trade receivables | 9,00,000 |
| c) Cash and cash equivalents | 2,28,000 |
| d) Short-term loans and advances | 72,000 |
| Total | 69,00,000 |
Free with a Super Tutor account
Free with a Super Tutor account
Free with a Super Tutor account
Free with a Super Tutor account
Free with a Super Tutor account
Total Assets Rs. 15,00,000
Current Liabilities Rs. 6,00,000
Total Debts Rs. 12,00,000
Free with a Super Tutor account
Inventory is Rs. 6,00,000; Liquid Assets Rs. 24,00,000; Quick Ratio 2 : 1.
Free with a Super Tutor account
Revenue from Operations Rs. 2,00,000
Gross Profit Rs. 50,000
Inventory at the end Rs. 60,000
Excess of inventory at the end over inventory in the beginning Rs. 20,000
Free with a Super Tutor account
(i) Current ratio (ii) Liquid ratio (iii) Operating Ratio (iv) Gross profit ratio
Current Assets Rs. 35,000
Current Liabilities Rs. 17,500
Inventory Rs. 15,000
Operating Expenses Rs. 20,000
Revenue from Operations Rs. 60,000
Cost of Revenue from operation Rs. 30,000
Free with a Super Tutor account
(i) Gross Profit Ratio (ii) Inventory Turnover Ratio (iii) Current Ratio (iv) Liquid Ratio (v) Net Profit Ratio (vi) Working Capital Ratio:
| Revenue from Operations | Rs. 25,20,000 |
|---|---|
| Net Profit | Rs. 3,60,000 |
| Cost of Revenue from Operations | Rs. 19,20,000 |
| Long-term Debts | Rs. 9,00,000 |
| Trade Payables | Rs. 2,00,000 |
| Average Inventory | Rs. 8,00,000 |
| Liquid Assets | Rs. 7,60,000 |
| Fixed Assets | Rs. 14,40,000 |
| Current Liabilities | Rs. 6,00,000 |
| Net Profit before Interest and Tax | Rs. 8,00,000 |
Free with a Super Tutor account
| Paid-up Share Capital | Rs. 5,00,000 |
|---|---|
| Current Assets | Rs. 4,00,000 |
| Revenue from Operations | Rs. 10,00,000 |
| 13% Debentures | Rs. 2,00,000 |
| Current Liabilities | Rs. 2,80,000 |
Free with a Super Tutor account
Inventory in the beginning is Rs. 76,250, Inventory at the end is Rs. 98,500, Sales is Rs. 5,20,000, Sales Return is Rs. 20,000, Purchases is Rs. 3,22,250.
Free with a Super Tutor account
| Inventory in the beginning of the year | Rs. 10,000 |
|---|---|
| Inventory at the end of the year | Rs. 5,000 |
| Carriage | Rs. 2,500 |
| Revenue from Operations | Rs. 50,000 |
| Purchases | Rs. 25,000 |
Free with a Super Tutor account
Free with a Super Tutor account
| 2015-16 | 2016-17 | |
|---|---|---|
| Trade receivables on Apr. 01 | Rs. 4,00,000 | Rs. 5,00,000 |
| Trade receivables on Mar. 31 | Rs. 5,60,000 | |
| Stock in trade on Mar. 31 | Rs. 6,00,000 | Rs. 9,00,000 |
| Revenue from operations(gross profit is 25% on cost ofRevenue from operations) | Rs. 3,00,000 | Rs. 24,00,000 |
Free with a Super Tutor account
(i) Debt-Equity Ratio (ii) Working Capital Turnover Ratio (iii) Trade Receivables Turnover Ratio
Balance Sheet as at March 31, 2017
| Particulars | Note No. | (Rs.) |
|---|---|---|
| I. Equity and Liabilities: | ||
| 1. Shareholders' funds | ||
| a) Share capital | 10,00,000 | |
| b) Reserves and surplus | 7,00,000 | |
| c) Money received against share warrants | 2,00,000 | |
| 2. Non-current Liabilities | ||
| Long-term borrowings | 12,00,000 | |
| 3. Current Liabilities | ||
| Trade payables | 5,00,000 | |
| Total | 36,00,000 | |
| II. Assets | ||
| 1. Non-current Assets | ||
| Fixed assets | ||
| - Tangible assets | 18,00,000 | |
| 2. Current Assets | ||
| a) Inventories | 4,00,000 | |
| b) Trade Receivables | 9,00,000 | |
| c) Cash and cash equivalents | 5,00,000 | |
| Total | 36,00,000 |
Additional Information: Revenue from Operations Rs. 18,00,000
Free with a Super Tutor account
ii) Inventory turnover ratio
| Rs. | |
|---|---|
| Inventory in the beginning | 50,000 |
| Inventory at the end | 60,000 |
| Net Profit | 2,17,900 |
| 10% Debentures | 2,50,000 |
| Revenue from operations | 4,00,000 |
| Gross Profit | 1,94,000 |
| Cash and Cash Equivalents | 40,000 |
| Money received against share warrants | 20,000 |
| Trade Receivables | 1,00,000 |
| Trade Payables | 1,90,000 |
| Other Current Liabilities | 70,000 |
| Share Capital | 2,00,000 |
| Reserves and Surplus | 1,20,000 |
| (Balance in the Statement of Profit & Loss) |
Free with a Super Tutor account
| Equity Share Capital | Rs. 75,000 |
|---|---|
| Share application money pending allotment | Rs. 25,000 |
| General Reserve | Rs. 45,000 |
| Balance in the Statement of Profit & Loss | Rs. 30,000 |
| Debentures | Rs. 75,000 |
| Trade Payables | Rs. 40,000 |
| Outstanding Expenses | Rs. 10,000 |
Free with a Super Tutor account
Free with a Super Tutor account
(i) Gross Profit Ratio (ii) Current Ratio (iii) Acid Test Ratio (iv) Inventory Turnover Ratio (v) Fixed Assets Turnover Ratio
| Rs. | |
|---|---|
| Gross Profit | 50,000 |
| Revenue from Operations | 1,00,000 |
| Inventory | 15,000 |
| Trade Receivables | 27,500 |
| Cash and Cash Equivalents | 17,500 |
| Current Liabilities | 40,000 |
| Land & Building | 50,000 |
| Plant & Machinery | 30,000 |
| Furniture | 20,000 |
Free with a Super Tutor account
| Revenue from Operations | Rs. 3,00,000 |
|---|---|
| Cost of Revenue from Operations | Rs. 2,40,000 |
| Inventory at the end | Rs. 62,000 |
| Gross Profit | Rs. 60,000 |
| Inventory in the beginning | Rs. 58,000 |
| Trade Receivables | Rs. 32,000 |
Free with a Super Tutor account
26 more solved questions in Accounting Ratios
They are free with a Super Tutor account, along with practice quizzes and flashcards for this chapter. Free to start, no card needed.
Frequently Asked Questions
What are the important topics in Accounting Ratios for CBSE Class 12 Accountancy?
Are these NCERT Solutions for Accounting Ratios free?
How should I revise Accounting Ratios for the CBSE Class 12 board exam?
Sources & Official References
- NCERT Official — ncert.nic.in
- CBSE Academic — cbseacademic.nic.in
- CBSE Official — cbse.gov.in
- National Education Policy 2020 — education.gov.in
Content is aligned to the official syllabus. Refer to the board website for the latest curriculum.
More resources for Accounting Ratios
Practice Quiz
Test yourself with a quick quiz
Important Questions
Exam-style questions with answers
Revision Notes
Key points for last-minute revision
Formula Sheet
The chapter's formulas in one place
Chapter Summary
Understand the chapter at a glance
Concept Maps
See how topics connect
Study Plan
Step-by-step plan for this chapter
Flashcards
Quick-fire cards for active recall
Syllabus
What topics to cover
For serious students
Get the full Accounting Ratios chapter — start free.
Quizzes, flashcards, an AI doubt solver and a study plan for CBSE Class 12 Accountancy. Free to start, no card needed.